Part 1
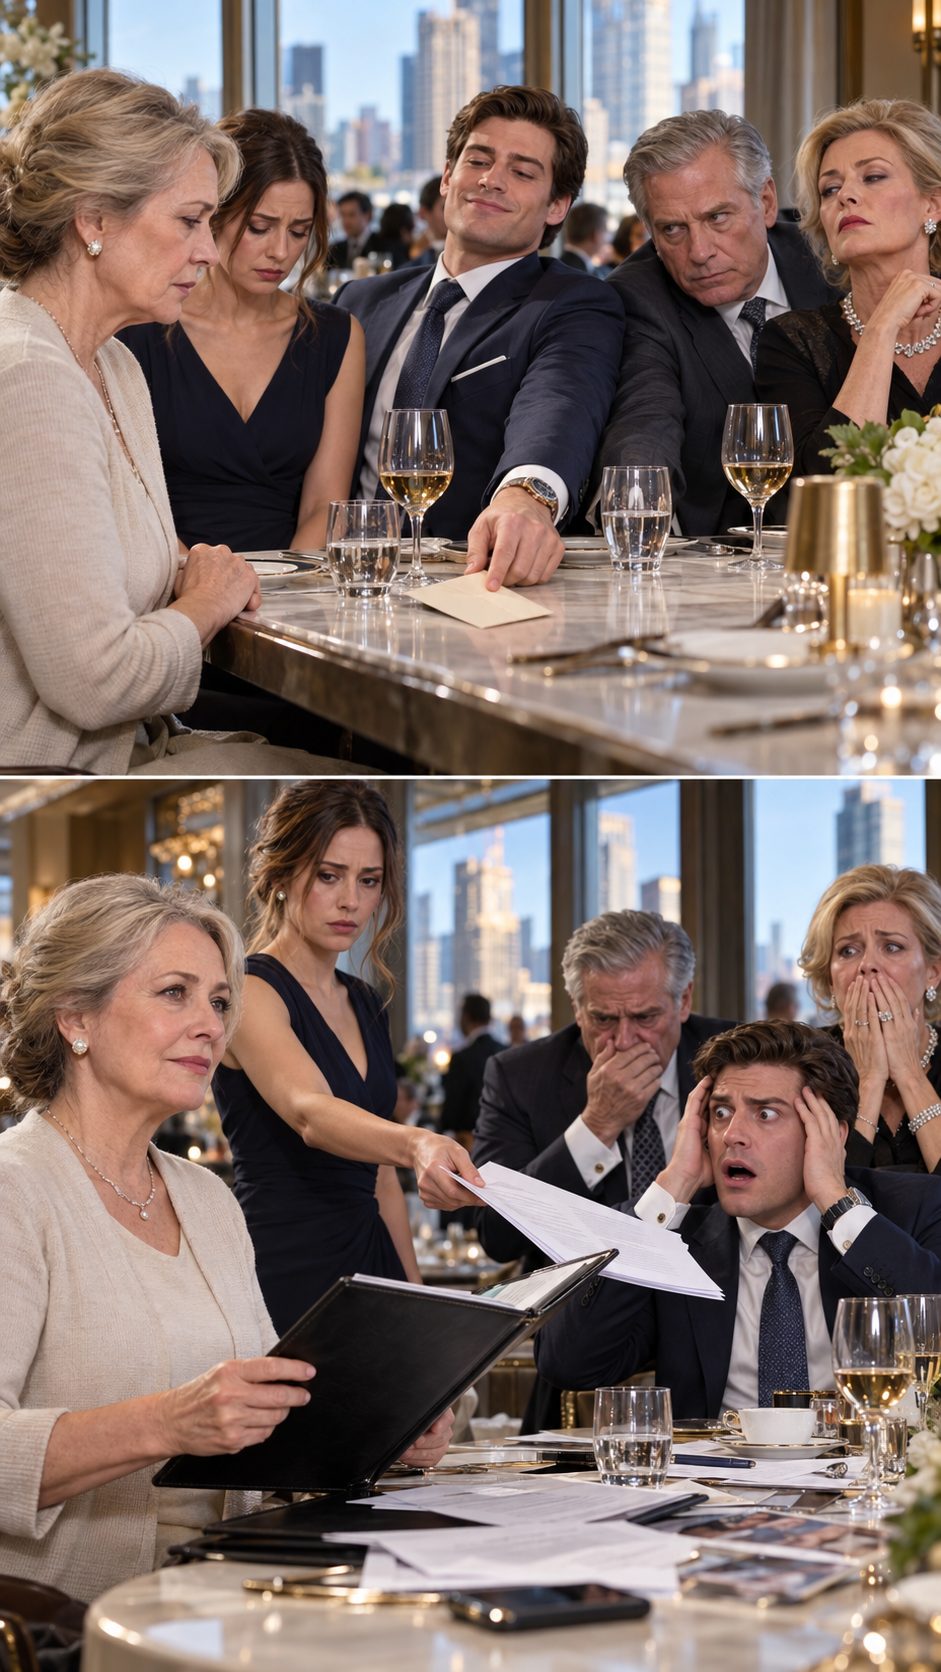
The envelope stopped directly in front of my plate, and my son-in-law smiled as if he had just purchased my silence. Two minutes later, his father told me, “For a woman living on a pension, Margaret, this is more money than you’ll ever see again.”
I looked at the cream-colored envelope.
Then I looked at my daughter Claire.
She was staring at the table.
That frightened me more than the insult.
Ethan had married Claire eighteen months earlier. He was polished, ambitious, and endlessly proud of his family’s real-estate company, Holloway Development. From the beginning, he treated me like furniture.
I drove a twelve-year-old Honda. I lived in the same small house I had owned for twenty-seven years. I wore department-store clothes and never discussed money.
Ethan had decided that meant I had none.
His mother, Denise, tapped the envelope.
“Open it.”
Inside was a cashier’s check for $40,000.
Underneath it was a legal document.
I read the first page slowly.
It stated that the $600,000 Claire had used toward the purchase of her marital home had been an unconditional gift to both Claire and Ethan. It also declared I had no financial interest in the property and would never challenge any future refinancing, transfer, or collateral agreement involving it.
My eyes lifted.
“What happens if I don’t sign?”
Ethan laughed.
His father, Richard, leaned back. “Then you make life unnecessarily difficult for your daughter.”
Claire flinched.
There it was.
The threat.
Ethan reached across the table and squeezed Claire’s wrist.
“Mom’s being dramatic,” he said. “We’re refinancing. Dad has a development opportunity. Everyone wins.”
“How large a loan?”
Silence.
Richard smiled.
“Three-point-two million.”
I folded the document.
“You want to use Claire’s home as security for your company.”
“Our family’s company,” Denise corrected sharply.
Claire finally whispered, “Mom, Ethan says it’s temporary.”
Ethan’s expression changed.
“Claire.”
One word.
A warning.
I understood immediately.
My daughter wasn’t agreeing.
She was being cornered.
I slipped the papers back into the envelope.
Richard smirked. “Forty thousand dollars is generous.”
“You’re right.”
His smile widened.
Then I pushed the check back.
“But not generous enough to buy my signature.”
Ethan’s face hardened.
“You should remember who’s supporting Claire now.”
I stood, picked up my purse, and kissed my daughter’s forehead.
“I remember exactly who supports whom.”
They laughed as I walked away.
None of them noticed that I had photographed every page.
And none of them knew that before becoming the harmless retiree Ethan mocked, I had spent thirty-one years finding financial fraud for people who thought they were much smarter than I was.
Part 2
The next morning, I made three phone calls.
The first was to my attorney.
The second was to the trustee controlling the fund that had purchased Claire’s house.
The third was to a former colleague who specialized in corporate forensic audits.
Because Ethan’s first mistake had been assuming the $600,000 came from my savings.
It hadn’t.
The house had been purchased partly through the Bell Family Property Trust, established after I sold my forensic-accounting firm nine years earlier.
After taxes, the sale had left me with a little over $14 million.
I had never told Ethan.
Claire knew I was comfortable, but even she didn’t know the full amount. Wealth had destroyed enough families during my career. I had no interest in letting mine become another.
More importantly, Ethan had never bothered reading the trust documents.
The trust’s contribution came with a restriction: no refinancing beyond a limited amount and no using the property to guarantee third-party business debt without trustee approval.
Richard’s proposed loan was impossible unless they could create paperwork suggesting the original money had been an unrestricted marital gift.
That explained the envelope.
But something else bothered me.
Why were they desperate?
My former colleague found the answer forty-eight hours later.
Holloway Development was drowning.
Richard had personally guaranteed multiple loans. Two apartment projects were months behind schedule. Contractors were unpaid. Tax liens had been filed against one subsidiary.
Then we found something worse.
A loan application had already been submitted.
Claire’s house appeared on the asset schedule.
Her supposed authorization was attached.
I stared at the signature.
My daughter’s name.
But not my daughter’s handwriting.
“Margaret,” my attorney said quietly, “they may have forged her consent.”
I called Claire.
“Did you sign anything Tuesday?”
“No.”
“Anything allowing Ethan to refinance the house?”
A long pause.
“No.”
Then she whispered, “Mom… what did he do?”
“Pack a bag.”
“What?”
“Documents, medication, anything important. Come to my house.”
That evening Ethan called me.
He didn’t bother pretending anymore.
“You’re poisoning my marriage.”
“I haven’t told Claire anything that isn’t documented.”
“You think because you balanced spreadsheets before retirement you understand business?”
I smiled.
“Yes.”
He laughed.
“Sign the paper, take your forty grand, and stay out of our lives.”
“I’ll consider your advice.”
He hung up believing he had intimidated me.
The next day, Richard made an even bigger mistake.
He emailed my attorney directly and threatened to sue me for interfering with the refinancing.
Attached to his email were revised documents.
One contained what appeared to be my signature.
I had never signed it.
That gave us exactly what we needed.
We notified the lender that the collateral documents were disputed and provided the trust agreement, handwriting samples, and Claire’s sworn statement.
The lender immediately suspended the application pending investigation.
Richard’s emergency financing disappeared overnight.
By Friday, unpaid contractors began filing claims.
By Monday, one of Holloway’s existing lenders demanded additional financial disclosures.
And Ethan still believed I had simply caused a temporary delay.
So when Denise invited me to a “final family discussion,” I accepted.
She chose the most expensive restaurant in town.
They arrived smiling.
I arrived with Claire, my attorney, and a black leather folder.
For the first time, Ethan stopped smiling before I sat down.
Part 3
Richard looked at my attorney.
“What is this?”
I placed the black folder on the table.
“The family discussion you requested.”
Denise’s voice sharpened. “This is private.”
“It stopped being private when someone submitted forged documents using my daughter’s property.”
Ethan turned toward Claire.
“You told her?”
Claire’s eyes filled with tears, but her voice stayed steady.
“You used my name.”
“I was protecting our future.”
“You forged my signature.”
Richard slapped his palm against the table.
“Enough! The company needed liquidity. Everything would have been repaid.”
I opened the folder.
“Would it?”
I slid several pages toward him.
Contractor claims.
Delinquent debt notices.
Tax records.
Internal financial statements obtained legally through lender disclosures and Claire’s marital financial records.
Richard went pale.
Denise stared at me.
“How did you get these?”
“I know where financial bodies are buried.”
Ethan scoffed nervously. “You were an accountant.”
“Forensic accountant.”
I paused.
“Then founder of Bell Forensic Advisory.”
Richard froze.
He knew the name.
Most developers did.
My company had spent decades investigating embezzlement, lender fraud, construction billing schemes, and hidden assets.
“I sold Bell nine years ago,” I continued. “That sale funded the trust that owns the protected interest in Claire’s house.”
Ethan’s mouth opened.
I turned to him.
“You spent eighteen months mocking my car, my clothes, and my ‘little pension.’ You were so busy calculating my value that you never bothered discovering who I was.”
Denise whispered, “How much are you worth?”
Claire stared at her.
“That’s still what you care about?”
Silence.
My attorney placed another document on the table.
“This confirms that the trust will not authorize the refinancing.”
Then another.
“This is notice that Claire is filing for divorce.”
Ethan shot to his feet.
“You can’t do this!”
Claire stood too.
“No. You did this.”
His anger vanished.
“Claire, please. Dad said we only needed the house for six months.”
“You let them forge my name.”
“I was going to tell you.”
“When? After we lost everything?”
Richard reached for the folder.
I closed it.
“There’s more.”
The lender had referred the disputed documents to its fraud department. Its internal review had uncovered discrepancies involving two other Holloway properties.
Their largest financing partner had frozen new advances that morning.
Richard’s face collapsed.
“You destroyed my company.”
“No,” I said. “I refused to let you use my daughter as the final piece of collateral for a company you had already destroyed.”
Denise began crying.
Not for Claire.
For herself.
“What are we supposed to do?”
I pushed the original $40,000 check across the table.
“You once told me this was more money than I’d ever see again.”
I stood.
“Keep it. You’re going to need it.”
Eight months later, Holloway Development entered bankruptcy restructuring. Richard lost two investment properties and was later indicted over fraudulent lending documents uncovered during the investigation. Denise sold their country-club home and moved into a rental condo.
Ethan accepted a settlement in the divorce after his attorney showed him how damaging the evidence could become in court. Claire kept her protected interest in the house and eventually sold it on her own terms.
As for me, I finally replaced my old Honda.
With another Honda.
Claire laughed when she saw it.
“You could buy anything.”
“I know.”
That was the point.
On Sunday mornings, Claire and I drank coffee on my porch, where no one cared what my clothes cost or what sat in my bank account.
One morning she asked, “Did you ever regret not telling Ethan you were wealthy?”
I looked across the quiet garden.
“No.”
“Why?”
“Because money wouldn’t have changed his character.”
I smiled.
“It only would have taught him to hide it better.”