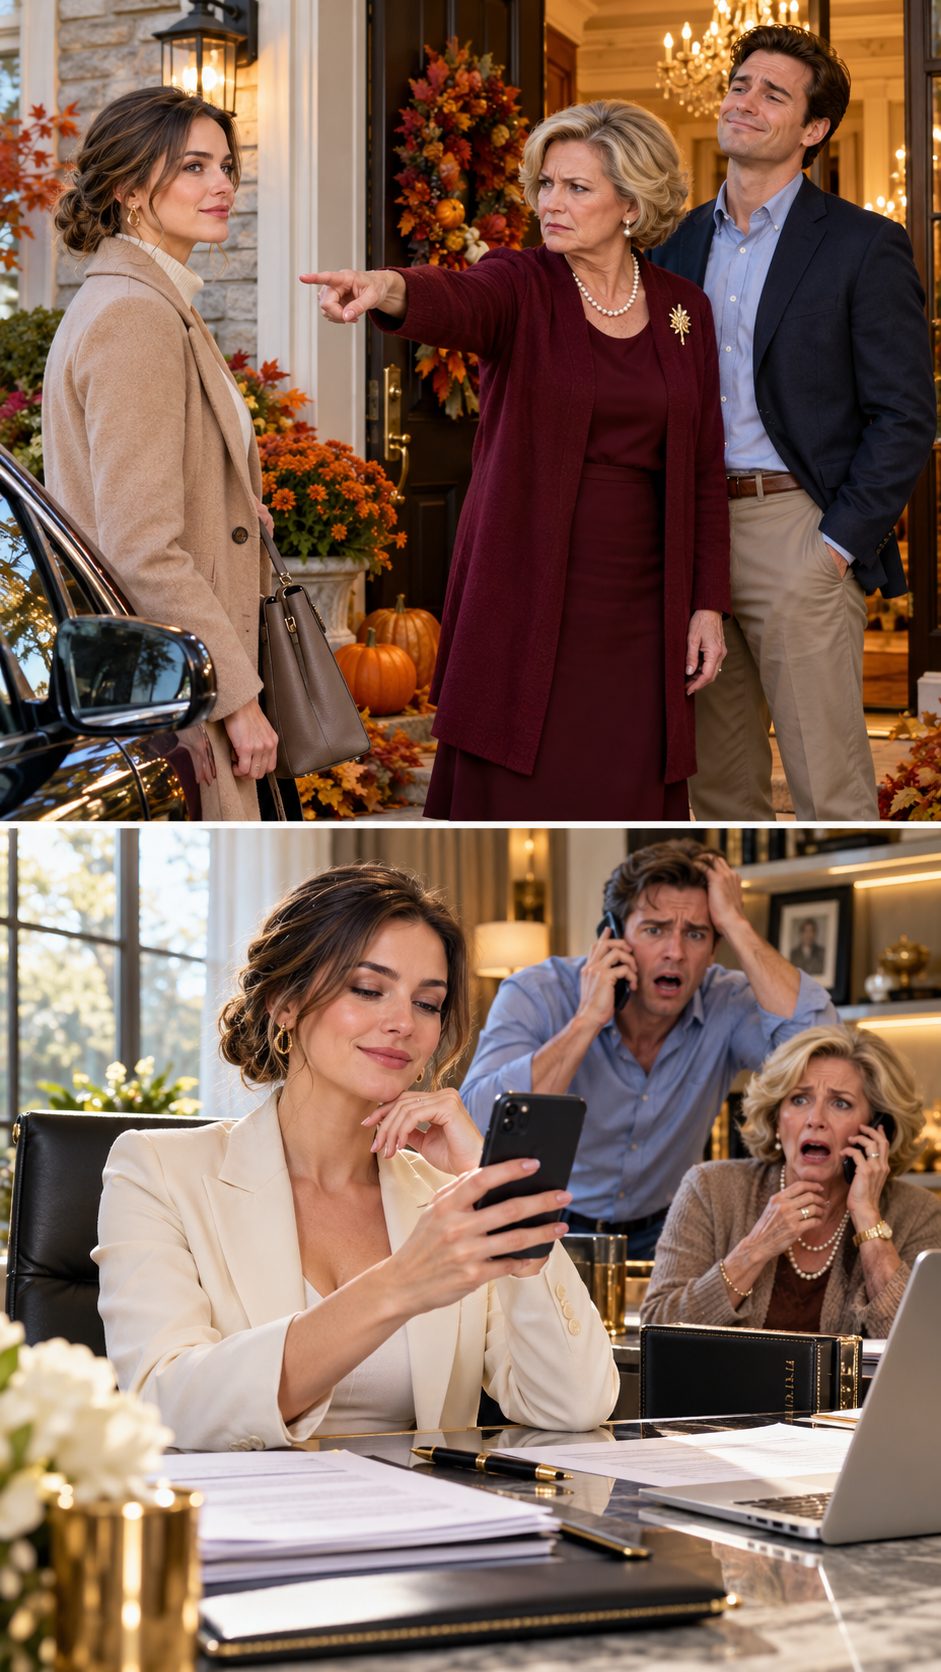
My mother-in-law looked me straight in the eye and said, “You’re not welcome at Thanksgiving.” My husband smiled beside her and added, “My mother’s word is law.”
For five seconds, nobody at the table moved.
I had spent three days preparing for that dinner.
The turkey was mine. The pies were mine. The groceries filling Patricia’s refrigerator had been bought with my card. Even the expensive wine she had proudly placed on the table came from a case I had ordered.
Yet there I was, standing in her doorway with my coat still on, being dismissed like an unwanted delivery driver.
Patricia folded her arms.
“This year is family only, Natalie.”
I looked at my husband, Mark.
“We’ve been married six years.”
He shrugged.
“Don’t start drama.”
His younger sister smirked behind her wineglass.
That was the moment something inside me went completely quiet.
For years, I had covered Mark’s mistakes because I thought that was what marriage meant.
When his consulting business failed, I paid our mortgage.
When Patricia needed a new roof, I quietly loaned her $18,000.
When Mark said his credit was temporarily damaged, I put his new SUV under my financing.
He loved telling people he was “the provider.”
I never corrected him.
That evening, I finally understood the difference between being generous and volunteering to be exploited.
I smiled.
“Okay.”
Mark blinked. “Okay?”
“Your mother’s house. Her rules.”
Patricia looked almost disappointed that I wasn’t crying.
I turned around, walked back to my car, and drove home.
Twenty minutes later, Mark texted me.
Don’t be childish. We’ll talk tomorrow.
I didn’t answer.
Instead, I opened the locked drawer in my home office.
Inside was a folder my attorney had prepared two months earlier after I discovered Mark had secretly transferred money from our joint account to cover debts from a business he had never told me existed.
I had not filed anything.
I had wanted to give him one final chance.
Thanksgiving made the decision for me.
By 8:30 p.m., I had frozen the joint credit card.
At 8:42, I transferred my salary into the individual account I had opened months earlier.
At 9:10, I emailed my attorney.
Proceed.
Then I opened the documents for Patricia’s roof loan.
Mark had convinced her I would “never ask for it back.”
Unfortunately for both of them, the signed repayment agreement said otherwise.
I poured myself a glass of wine, turned off my phone, and slept better than I had in years.
The next morning, I turned it back on.
Fifty-two missed calls.
And it was only 7:18 a.m.
Part 2
The first voicemail was from Mark.
“Natalie, call me immediately.”
The seventh was louder.
“What did you do to the cards?”
By voicemail fourteen, anger had become panic.
“My car payment bounced. Fix this.”
Patricia appeared around voicemail twenty-three.
“Natalie, family doesn’t behave this way.”
I actually laughed.
Apparently, family rules had changed overnight.
Then I saw the email that explained the panic.
Mark had planned to use our joint credit line that morning to make a $12,000 payment to a private lender.
Without it, he was in default.
I called my attorney, Daniel.
“Did you know about this lender?”
“No,” he said. “But now we do.”
Within an hour, we found more.
Mark had formed another company nine months earlier.
He had borrowed aggressively, personally guaranteed portions of the debt, and used our shared household income on applications without telling me.
Worse, he had apparently promised investors access to property he did not own.
My property.
The house Mark constantly called “our house” had actually been purchased by me three years before our marriage.
His name had never been added to the deed.
That detail suddenly mattered.
At 10:06, Mark arrived home.
He stormed into my office.
“What the hell are you doing?”
I closed my laptop.
“Protecting myself.”
“You froze my money.”
“No. I froze a joint credit account attached primarily to my income.”
His face reddened.
“Unlock it.”
“No.”
He stared at me.
Then he laughed.
“You’re seriously throwing away six years because Mom didn’t invite you to dinner?”
“This isn’t about dinner.”
“Then what is it about?”
I slid a printed document across the desk.
His face changed immediately.
It was a loan application bearing my financial information.
And a signature that looked like mine.
Almost.
“You want to explain that?”
He stared at the page.
“It was paperwork.”
“You signed my name.”
“I was going to tell you.”
“When?”
Silence.
I placed another paper beside it.
Divorce petition.
His mouth opened.
“You’re bluffing.”
“No.”
“You can’t just take everything.”
“I’m not taking anything that belongs to you.”
That sentence frightened him more than yelling would have.
He started pacing.
“My mother was right about you. You’ve always thought you were better than us because you make more money.”
“No, Mark. I just finally realized you think my money belongs to you.”
Then his phone buzzed.
He checked it.
The lender.
Again.
He looked at me with something close to hatred.
“You planned this.”
“No. You did.”
That afternoon, Patricia called directly.
“You need to stop punishing my son.”
“I’m not.”
“You’re destroying his business.”
“His business appears to be destroying itself.”
She snapped, “After everything we’ve done for you!”
That one was almost impressive.
I emailed her a copy of the signed roof-loan agreement.
Her tone changed instantly.
“What is this?”
“Something you signed.”
“You wouldn’t.”
“I haven’t decided yet.”
For the first time since I had known Patricia, she had nothing to say.
Then Mark made his final mistake.
That evening, Daniel called me.
“Natalie, we found evidence he tried to pledge the house as collateral.”
I looked around the office I had paid for.
“Can he?”
“No.”
“Good.”
Daniel paused.
“And there’s more.”
Mark’s lender had already discovered the ownership problem.
They were preparing to come after him personally.
I leaned back in my chair.
Thanksgiving had ended less than twenty-four hours earlier.
And suddenly, nobody was telling me whose word was law.
Part 3
Three days later, Mark sat across from me in Daniel’s conference room.
His arrogance was gone.
His attorney sat beside him.
So did Patricia.
She had insisted on coming because, according to Mark, “this affected the whole family.”
For once, he was right.
Daniel opened the meeting.
“The residence is Natalie’s separate property. The vehicle financing is in her name, though Mark has been making some payments. The disputed credit accounts are being reviewed, and the forged signature has been reported to the lender.”
Patricia slammed her hand on the table.
“Forged? Don’t use that word.”
Daniel looked at her calmly.
“What word would you prefer for signing another person’s name without permission?”
Her face went rigid.
Mark turned toward me.
“You reported me?”
“I documented what happened.”
“We’re married!”
“That didn’t give you permission.”
His attorney quietly touched his arm, warning him to stop talking.
Then Daniel moved to Patricia’s loan.
“Regarding the $18,000 roof advance, the agreement requires repayment upon demand if the borrower violates the payment schedule.”
Patricia looked at me.
“You promised me that was a gift.”
“No. Mark promised you I’d never collect.”
She turned on him.
“You said she agreed!”
Mark said nothing.
It was almost poetic.
The two people who had spent years using me as their shared financial safety net suddenly realized they had also been lying to each other.
I did not demand Patricia’s house.
I didn’t need cruelty to make the point.
We agreed to a structured repayment plan she could actually afford.
Mark was different.
His private lender accelerated the debt after learning the collateral claim was invalid.
His consulting company collapsed within weeks.
The SUV was voluntarily surrendered because I refused to continue financing a luxury vehicle for a man divorcing me.
During mediation, Mark demanded half the value of my house.
He received none of it.
The property records, purchase date, and financial history were clear.
He did receive his share of legitimate marital assets.
I wanted a clean divorce, not a fantasy victory.
But clean was devastating enough.
His debts consumed most of what remained.
The forged-signature issue was eventually settled without criminal prosecution after the lender accepted repayment terms and Mark signed a formal admission regarding the unauthorized application.
My attorney advised me that certainty was better than years of litigation.
I agreed.
Patricia called me once before the divorce became final.
Her voice sounded smaller.
“I never thought you’d actually leave.”
“That was the problem.”
She went quiet.
Then she said, “Mark says you ruined his life.”
I looked out the window of my office.
“No. Mark built a life that only worked as long as I kept paying for it.”
Six months later, the divorce was final.
I renovated the house.
Not dramatically.
I simply removed everything that had been chosen to please someone else.
Mark moved into a one-bedroom apartment and took a salaried job after his business disappeared.
Patricia never missed another roof payment.
And Thanksgiving came again.
This time, I hosted.
My parents came. Two friends came. Daniel and his wife stopped by for dessert.
At 6:14 p.m., my phone buzzed.
A message from Mark.
Hope you’re happy.
I looked around the table.
People were laughing.
Nobody was insulting me.
Nobody was using my credit.
Nobody was telling me I should accept humiliation because “family” demanded it.
I deleted the message.
Then I raised my glass.
The year before, I had driven home alone thinking I had been excluded from Thanksgiving.
I understand now.
They hadn’t excluded me.
They had released me.
And those fifty-two missed calls the next morning weren’t proof that they loved me.
They were proof that the people who treated me as disposable had finally discovered how much of their lives depended on the woman they told to leave.