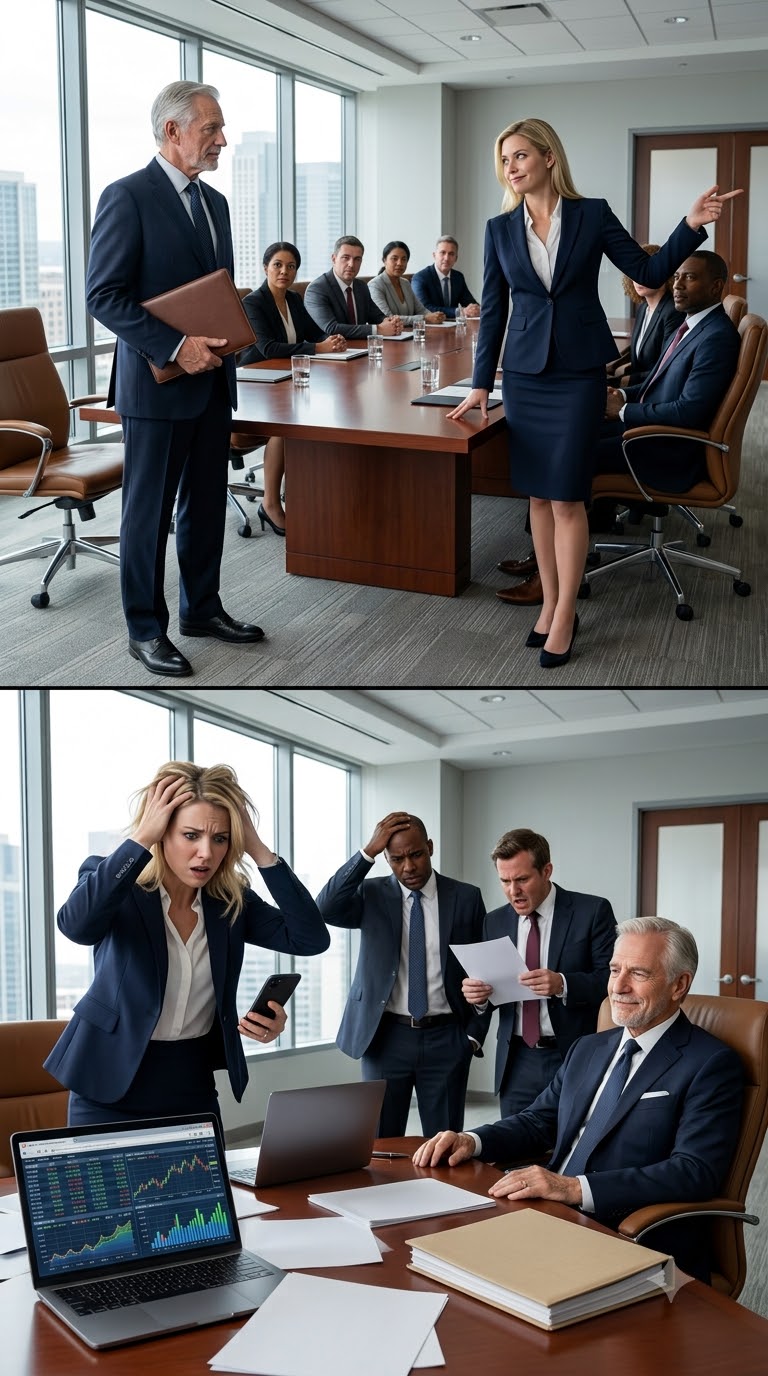
“Your methods are outdated. I’m taking over from today.” My granddaughter said it in front of twelve directors on her first morning as CEO, then slid a termination letter across the boardroom table as if forty-three years of my life could be erased with one signature.
I looked at Caroline Mercer—twenty-nine years old, immaculate navy suit, MBA from Wharton, confidence sharpened by people who had never allowed her to fail.
Behind her, the screen displayed our company logo:
Mercer Industrial Systems.
My name.
My company.
Or at least, the company I had built from a rented machine shop into a manufacturing group employing eleven hundred people.
I had stepped down as CEO two years earlier but remained executive chairman while preparing Caroline to succeed me.
Apparently, she had interpreted preparation as surrender.
“You’re firing me?” I asked.
“Retiring you,” she corrected.
A few directors shifted uncomfortably.
Caroline smiled.
“We need speed, automation, aggressive expansion. Not caution.”
“Caution kept us alive through three recessions.”
“And caution is why our competitors are growing faster.”
She tapped the termination letter.
“Your office will be cleared by Friday.”
I looked toward Martin Hale, our lead independent director.
He avoided my eyes.
So they had planned this.
Caroline continued.
“I’ve already reorganized treasury authority. I’ll personally approve major spending.”
That finally got my attention.
“Personally?”
“Yes.”
“And the bank?”
She rolled her eyes.
“The bank doesn’t run this company.”
“No,” I said. “But you may want to read our credit agreement.”
Martin cleared his throat.
“Arthur, let’s keep this civil.”
I stood.
“If I leave today under these conditions, all of you are going to regret it.”
Caroline actually laughed.
“Are you threatening us?”
“No.”
I buttoned my jacket.
“I’m warning you.”
She leaned back with a triumphant smile.
“Same thing old men say when they realize nobody needs them anymore.”
That hurt.
Not because she called me old.
Because when Caroline was seven, her father—my only son—died in a car accident. I raised her through half her childhood.
I paid for college.
I taught her to read a balance sheet at my kitchen table.
And somewhere along the way, she had decided gratitude was weakness.
I left without arguing.
At home, I opened a locked cabinet and removed a copy of Mercer Industrial’s $42 million revolving-credit agreement.
Page 117.
Section 9.4.
Key Management and Control Covenant.
The bank had approved Caroline as my eventual successor—but only after a six-month transition with me remaining executive chairman and authorized guarantor liaison.
Immediate removal without written bank consent constituted a review event.
Then I opened the email Caroline had sent treasury two days earlier.
Effective immediately, transfer $8 million from liquidity reserves into the Atlas acquisition account.
An acquisition the board had not yet approved.
I picked up my phone.
“Daniel,” I said when our banker answered, “I’m no longer executive chairman.”
Silence.
Then:
“Arthur… does the board know what that triggers?”
I looked at Caroline’s termination letter.
“They’re about to.”
Part 2
At 8:07 the next morning, Mercer Industrial’s treasury director tried to release payroll funding.
The transfer failed.
At 8:11, the corporate credit line stopped accepting draws.
At 8:19, outbound transfers above $50,000 were placed under review.
By 8:26, Caroline had called me four times.
I let the phone ring.
The bank had not “stolen” our money. It had placed temporary controls on large transactions and suspended the revolving facility while reviewing a governance change that violated the credit agreement.
Exactly what Section 9.4 allowed.
Caroline called again.
This time I answered.
“What did you do?” she shouted.
“I notified the bank that I had been removed.”
“You froze our accounts!”
“No. The bank responded to your decision.”
“Fix it.”
“Ask your board.”
She hung up.
At 9:30, Martin called.
“Arthur, we may have moved too quickly.”
“You think?”
“We need you to tell Daniel this is a misunderstanding.”
“It isn’t.”
There was a pause.
Then he lowered his voice.
“Payroll is Friday.”
“You still have unrestricted cash for payroll.”
Another pause.
So they hadn’t even checked.
They were panicking because Caroline told them to.
That was my first clue that the problem was larger than arrogance.
At noon, our chief financial officer, Helen Cho, came to my house.
She looked exhausted.
“Arthur, Caroline tried to move the eight million again.”
“After the bank review started?”
“Yes.”
“Why?”
Helen placed a folder on my dining table.
“Atlas.”
Atlas Robotics was the startup Caroline wanted Mercer Industrial to acquire.
She had described it as a “transformational AI manufacturing platform.”
The board presentation valued it at $31 million.
Helen had found something else.
“Caroline’s college roommate is Atlas’s chief operating officer.”
I said nothing.
Helen turned another page.
“And her fiancé’s venture fund owns nineteen percent.”
My stomach dropped.
“Was that disclosed?”
“No.”
Now the eight-million-dollar transfer looked very different.
Not necessarily criminal.
But absolutely a conflict requiring disclosure.
“Does Martin know?”
“He does now.”
At 2:15, the board convened an emergency meeting without Caroline.
I attended remotely at their request.
Martin looked ten years older than he had the day before.
“Arthur,” he said, “did you know about Atlas?”
“No.”
Helen presented the ownership records, emails, and Caroline’s instruction to move funds before final approval.
One director swore under his breath.
Another asked, “Why would she rush this?”
Helen answered carefully.
“Because Atlas has a debt payment due Monday.”
Silence.
There it was.
Caroline had not simply wanted modernization.
She had wanted company money moved quickly enough to rescue a business tied to people close to her.
At 4:40, Caroline entered the meeting furious.
“You met without me?”
Martin said, “Sit down.”
She looked at me on the screen.
“This is his revenge.”
I leaned toward the camera.
“No. My revenge would require me to do something.”
“You called the bank!”
“I complied with the credit agreement.”
“You knew what would happen.”
“Yes.”
Her face hardened.
“You set me up.”
“No, Caroline.”
I held up her own email.
“You fired the one person who kept telling you to read before you signed.”
That evening, the bank sent its conditions for restoring full access.
Independent governance review.
Suspension of the Atlas transfer.
Temporary dual authorization for major payments.
And confirmation of compliant leadership oversight.
Caroline read the letter.
Then, according to Helen, she whispered:
“They can’t do this to me.”
Helen replied:
“They already did.”
Part 3
Two mornings later, I returned to the boardroom where Caroline had fired me.
This time, nobody avoided my eyes.
Caroline sat at the far end of the table instead of the head.
Martin occupied the center seat.
A corporate attorney sat beside him.
Helen was present.
So was an outside governance adviser.
Caroline stared at me.
“You enjoying this?”
“No.”
“You expect me to believe that?”
“I expected you to be better than this.”
For the first time, her expression flickered.
Martin opened the meeting.
“The independent review has confirmed that Caroline failed to disclose material personal relationships connected to the proposed Atlas acquisition.”
Caroline immediately interrupted.
“I wasn’t personally invested.”
“That isn’t the standard,” the attorney said.
Martin continued.
“She also instructed treasury to initiate acquisition funding before final board authorization.”
“I was moving quickly!”
“You were bypassing controls.”
“I was saving the company from people like him!”
She pointed at me.
I stayed silent.
Then Helen displayed a timeline.
Caroline had pushed Atlas for months.
She had pressured financial staff to accelerate diligence.
She had described my objections to the board as “emotional resistance to innovation.”
And she had concealed the fact that her fiancé’s fund stood to benefit if Mercer Industrial rescued Atlas.
Caroline’s face slowly lost color.
“It wasn’t illegal.”
The attorney answered.
“That determination isn’t yours to make. The issue before this board is your judgment and disclosure obligations.”
Martin folded his hands.
“Caroline, effective immediately, you are suspended as CEO pending final review.”
Her mouth opened.
Nothing came out.
Then she looked at me.
“You planned this.”
“No.”
“You knew the bank would freeze us.”
“I knew the agreement you signed without reading would trigger review.”
“You could have warned me!”
I almost laughed.
“I did.”
The room went silent.
Her own words returned to us.
Your methods are outdated.
You’re trying to scare us.
Nobody needs you anymore.
Martin finally looked at me.
“Arthur, the board would like you to return as interim executive chairman while we stabilize operations.”
I shook my head.
Caroline looked surprised.
So did everyone else.
“No.”
Martin blinked.
“We need you.”
“You need governance, not a grandfather cleaning up another mess.”
I agreed to serve sixty days as an unpaid adviser, nothing more.
The bank restored normal operating access four days later after the board accepted enhanced controls and canceled the Atlas transaction.
Payroll went out on time.
No factories closed.
No employees lost wages.
Atlas failed to refinance and entered restructuring six weeks later.
Caroline’s fiancé’s fund suffered a substantial loss.
Their engagement ended shortly afterward.
The board’s final review concluded that Caroline had exercised poor judgment, failed to disclose conflicts, and attempted to circumvent approval procedures.
She resigned before they could formally remove her.
I did not stop them.
That was the part she never understood.
I had spent years protecting her from consequences because I loved her.
Then she mistook protection for proof that consequences didn’t exist.
Eight months later, Mercer Industrial had a new CEO: Helen Cho.
Revenue was growing again.
Our debt had fallen.
And for the first time in decades, I no longer had an office.
I liked that more than I expected.
One Sunday afternoon, Caroline came to my house.
No suit.
No arrogance.
Just my granddaughter standing on the porch.
“I thought being decisive meant never hesitating,” she said.
I poured two coffees.
“It means knowing what deserves hesitation.”
She looked down.
“I humiliated you.”
“Yes.”
“I’m sorry.”
I believed her.
Forgiveness came slowly, but it came.
Reinstatement did not.
Some lessons disappear when consequences do.
Before she left, Caroline looked at me and said, “You really didn’t freeze the accounts?”
I smiled.
“No.”
“Then why did everything collapse the minute you left?”
I looked toward the framed photograph of the first Mercer factory.
“Because, Caroline, you thought the old man was standing in the way.”
I paused.
“You never realized he was standing underneath it.”