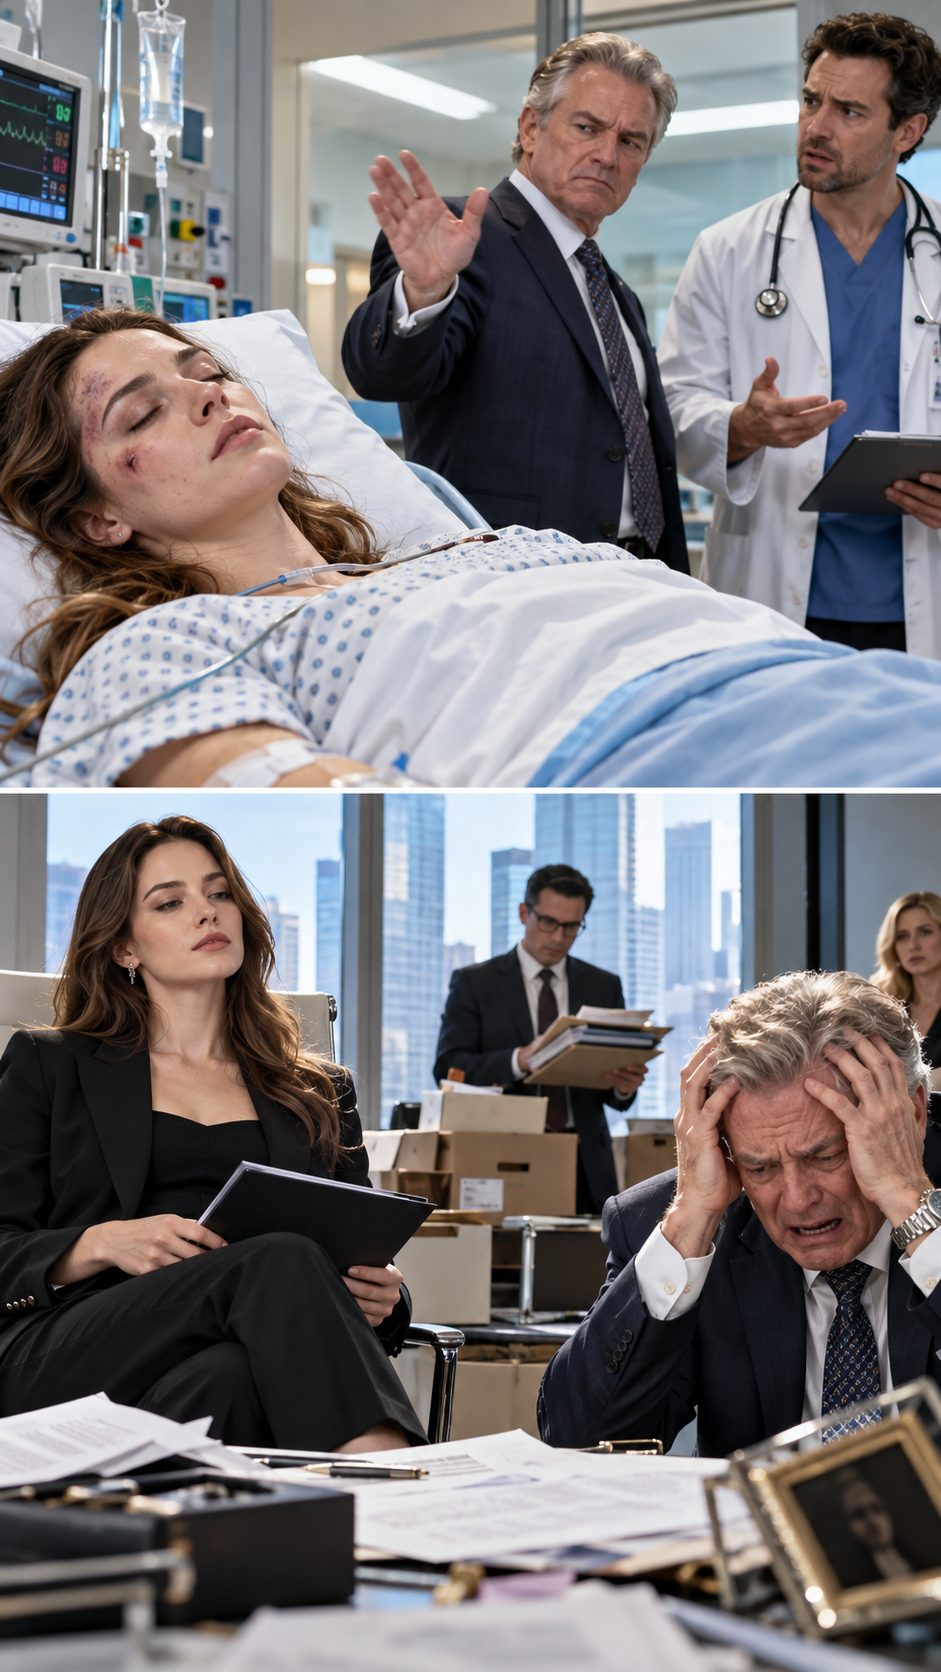
The first thing I heard after waking from a four-day coma was my father telling a doctor I wasn’t worth saving. The second thing I learned was that while I’d been unconscious, he had been using my name to save the company that had nearly killed me.
Three days earlier, I had been driving home from a late meeting when a delivery truck ran a red light and crushed the driver’s side of my car.
I remembered glass.
Metal screaming.
Then nothing.
What I didn’t remember was my father standing outside the ICU, arguing with Dr. Keller.
“The deductible alone is ridiculous,” he said.
Dr. Keller’s voice sharpened. “Your daughter needs another procedure.”
My father sighed.
“Let her go. She’s not worth paying the insurance deductible.”
A nurse later told me those words.
She had heard everything.
When my eyes finally opened, Dad was sitting beside my bed pretending to be devastated.
“Oh, thank God,” he whispered, squeezing my hand. “Emily, you scared us.”
I stared at him.
I said nothing.
He mistook my silence for weakness.
That had always been his favorite mistake.
My father, Richard Hayes, owned Hayes Industrial Supply, a company my grandfather had started forty years earlier.
Dad loved telling people he had built it himself.
He hadn’t.
For the last six years, I had been quietly rebuilding it after his reckless expansions, bad loans, and habit of treating company accounts like his private wallet.
I was the chief financial officer.
More importantly, I owned forty percent of the voting shares.
Dad owned thirty-five.
The rest belonged to a family trust.
He needed my signature for major debt agreements.
And while I was unconscious, he forged it.
I discovered that two hours after waking.
My phone had been placed in a hospital drawer. When the nurse finally returned it, I saw twenty-seven banking alerts and an email from our corporate attorney.
Emily, I need confirmation that you personally approved the emergency revolving credit amendment. The signature looks inconsistent.
The agreement carried my name.
It authorized $3.8 million in new debt.
I had never seen it.
Dad came back into the room holding coffee.
“You should rest,” he said. “I’ll handle the company until you recover.”
I looked at him.
Then at the forged document.
Then back at him.
He smiled.
For the first time in my life, I understood exactly what my father thought I was.
A signature.
A salary.
A problem he could switch off when the cost became inconvenient.
I smiled weakly.
Then I typed one message beneath the blanket.
Do not confront him. Freeze nothing yet. Prepare the emergency shareholder provisions.
I sent it to our attorney.
Dad never noticed.
He was too busy celebrating the fact that I was alive just enough to remain useful.
PART 2
I left the hospital two days later against my father’s recommendation.
Not the doctor’s.
My father’s.
“You’re in no condition to work,” Dad told me as he drove me home.
“I agree.”
That answer relaxed him.
He thought the accident had finally made me obedient.
The next morning, he called an emergency executive meeting without inviting me.
By noon, my assistant had sent me the recording.
Dad sounded almost cheerful.
“Emily will be out for months. We move forward without her.”
One manager asked, “What about the new credit facility?”
“Handled.”
“And her approval?”
Dad laughed.
“She approved what she needed to approve.”
My stomach turned.
But I kept listening.
Then came the sentence that ended whatever loyalty I had left.
“If she becomes difficult, we can restructure her position. People recover from accidents differently. Cognitive issues, emotional instability—who knows?”
He was already preparing to discredit me.
Unfortunately for him, he had overlooked something.
Two years earlier, after discovering unexplained transfers from the company into a private development project owned by Dad and my brother, I had convinced the board to amend our corporate bylaws.
Dad barely read the documents before signing.
The amendment created an emergency protection clause.
If any officer used fraudulent authorization to incur debt, divert assets, or expose the company to material liability, the independent shareholder representative could immediately suspend that officer’s authority pending investigation.
The family trust’s independent representative?
My grandmother.
And she hated thieves.
At 3:10 that afternoon, I video-called her.
I showed her the forged signature.
Then the bank records.
Then the executive recording.
Grandma stared silently for several seconds.
Finally she said, “Your grandfather built that company so his children would have something honorable.”
“I know.”
“And Richard used your signature?”
“Yes.”
She leaned closer to the camera.
“What do you need from me?”
“Nothing illegal. Nothing dramatic. Just your vote.”
She smiled.
“That sounds dramatic enough.”
The next step was the bank.
The $3.8 million facility Dad had obtained through my forged authorization contained a fraud representation clause. If the authorization was false, the lender could immediately revoke the undrawn portion and demand additional collateral on existing obligations.
Dad had already moved $1.4 million into his failing real-estate project.
He believed he had bought himself six months.
He had actually created a trap.
At 8:00 the next morning, our attorney notified the board.
At 8:07, Grandma exercised the trust’s voting rights.
At 8:16, Dad was suspended as president.
At 8:31, the bank’s fraud department opened its investigation.
At 9:02, I received my father’s first call.
I declined it.
Then another.
Then eleven more.
Finally, he sent a text.
WHAT DID YOU DO?
I looked at the message for a long time.
Then replied with four words.
I verified my signature.
His response came instantly.
YOU’RE DESTROYING THIS FAMILY.
I laughed for the first time since waking up.
Because men like my father always called it “family” when they meant access.
By noon, the bank had frozen further draws.
By 2:00 p.m., a second lender invoked a cross-default review.
By 4:30, Dad’s private development company lost its bridge financing.
And that was when he finally understood.
The daughter he had decided wasn’t worth an insurance deductible controlled the one thing keeping his empire alive.
Consent.
PART 3
Dad arrived at my house at 6:12 that evening.
He didn’t knock.
He hammered on the door.
“Emily!”
I opened it but kept the security chain latched.
He looked twenty years older than he had that morning.
“What the hell have you done?”
“I reported fraud.”
“You reported your own father!”
“You forged my signature.”
“To save the company!”
“You transferred company money into your personal project.”
His face changed.
That was the moment he realized I knew everything.
“That was temporary.”
“So was my coma.”
He flinched.
I continued.
“And apparently my life was temporary too, if the deductible got inconvenient.”
His mouth opened.
Nothing came out.
I had never told him the nurse repeated his words.
Now I watched the blood drain from his face.
“You heard that?”
“No.”
I paused.
“Someone decent did.”
“Emily, I was scared. I didn’t mean it.”
“You told a doctor to let your unconscious daughter die because treatment was expensive.”
“That’s not what happened.”
“It’s exactly what happened.”
He lowered his voice.
“Listen to me. If the lenders pull out, I lose everything.”
I stared at him.
“That’s the first honest thing you’ve said.”
His anger returned.
“You think you win if I lose? The company collapses too.”
“No.”
I unlatched the chain and handed him a folder.
He opened it.
His eyes raced across the first page.
“What is this?”
“A restructuring agreement.”
Hayes Industrial Supply’s profitable operating assets had been separated from Dad’s speculative property venture months earlier.
Another safeguard I had designed.
The board had approved the sale of the healthy operating division to a newly formed employee-owned holding company financed by a private lender I had been negotiating with for weeks.
The company would survive.
Its workers would keep their jobs.
Dad’s personal guarantees would not.
He flipped through the pages faster.
“No.”
“The warehouse stays.”
“No.”
“The contracts stay.”
“Emily—”
“The employees stay.”
His hands began shaking.
“And you,” I said quietly, “keep exactly what you personally chose to guarantee.”
The real-estate project.
Two commercial loans.
A line of credit secured by his house.
The debt tied to the forged agreement triggered reviews across every facility carrying his personal guarantees.
By the following morning—less than twenty-four hours after the board suspended him—Dad’s private company was insolvent.
His development property entered receivership.
The bank began foreclosure proceedings on two investment properties.
The company car disappeared from his driveway.
So did the illusion that he had been the powerful one.
He called everyone.
Grandma refused him.
My brother blamed him.
The board removed him permanently.
Investigators later referred the forged documents to authorities. Dad eventually accepted a plea agreement involving probation, restitution, and a prohibition against serving as a corporate officer during the supervision period.
He never went back to Hayes Industrial Supply.
Neither did I.
Six months later, I sold most of my shares to the employee trust.
I kept a small stake.
Not because I needed control.
Because my grandfather had once told me ownership should mean responsibility, not domination.
A year after the accident, I stood beside the ocean outside a small house I had bought with money that belonged entirely to me.
No family accounts.
No hidden agreements.
No signatures anyone else could borrow.
My father sent one final email.
I hope one day you understand I was trying to save what I built.
I read it once.
Then deleted it.
Because he still didn’t understand.
He had spent his life believing buildings, companies, money, and obedience were things a man could own forever.
But the moment he looked at his unconscious daughter and decided she was worth less than a bill, he lost the only thing I had ever given him freely.
My loyalty.
And unlike his debts, that was something he could never refinance.