Part 1
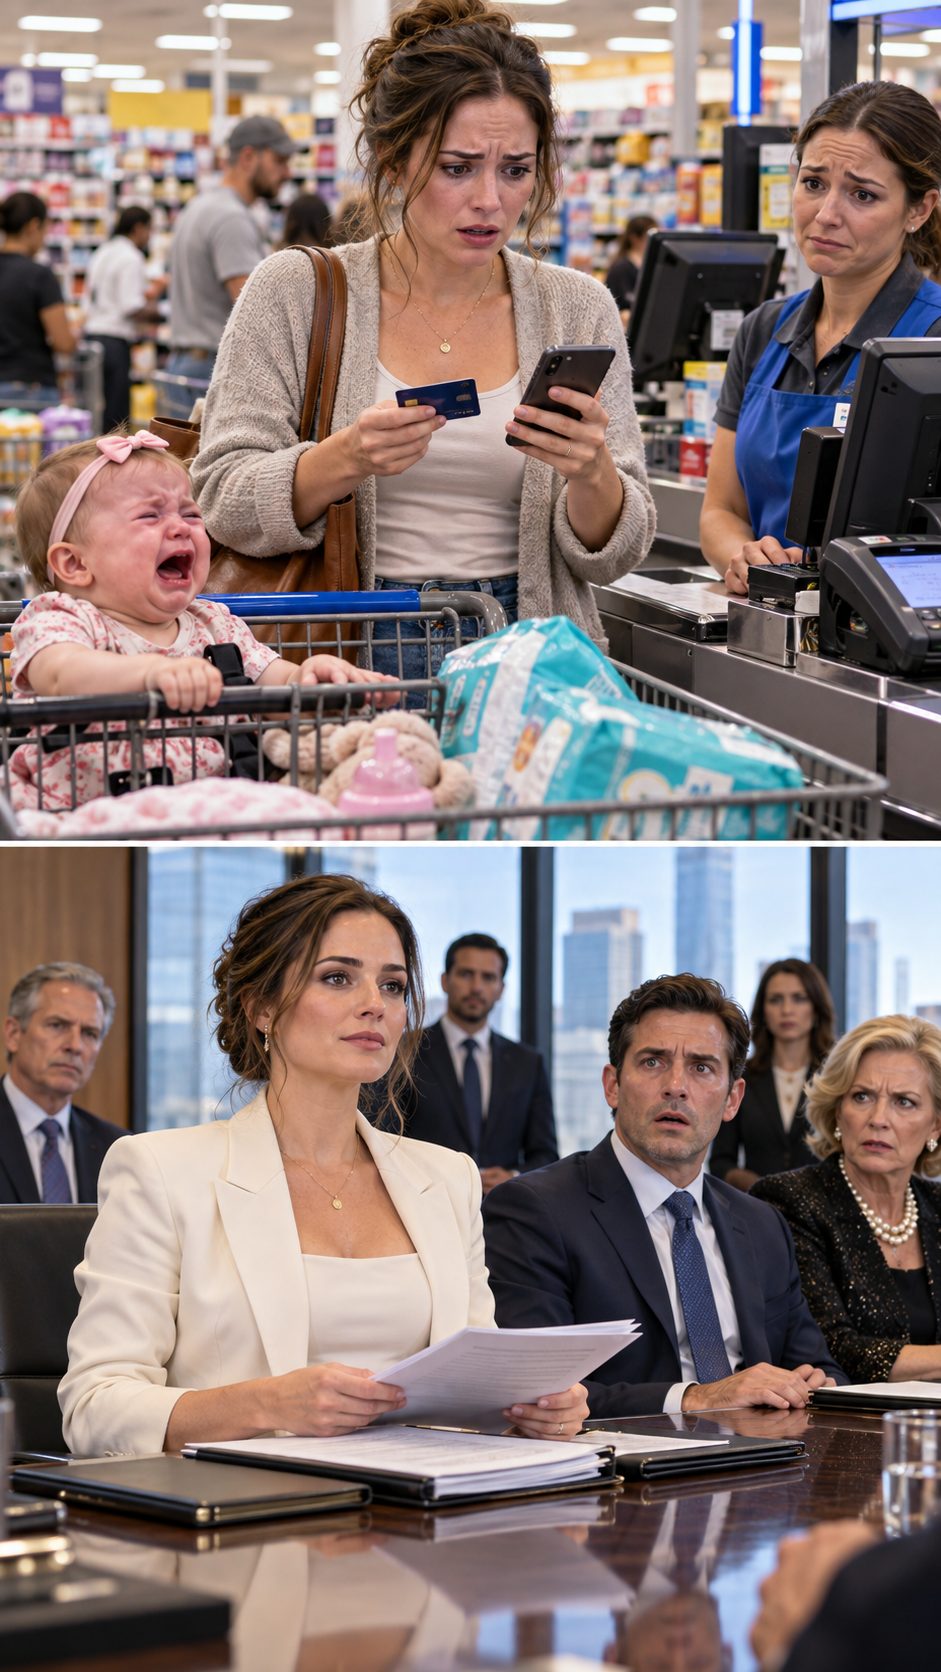
The cashier swiped my card twice before lowering her voice. “I’m sorry, ma’am. It says the account has been frozen.” My six-month-old daughter was crying in the cart, and the diapers in front of me suddenly felt more expensive than diamonds.
I stepped aside and called my husband.
Evan answered on the second ring.
“You froze my card?”
He laughed.
Not nervous laughter. Not confused laughter.
Satisfied laughter.
“I told you we needed to talk about your spending.”
“My spending?” I whispered. “I’m buying diapers.”
“You bought coffee yesterday.”
For a moment, I thought he was joking.
Then he said, “Maybe this will teach you to ask before using my money.”
My money.
That was almost funny.
For four years, I had stayed home while raising our daughter and helping Evan build Mercer Development from a three-person construction firm into a company bidding on multimillion-dollar projects. Before maternity leave, I had been a corporate accountant. I built his budgets, negotiated his first serious bank financing, and caught two subcontractors overbilling him.
But once the money started coming in, Evan rewrote history.
His mother, Patricia, helped.
“She’s lucky you provide for her,” Patricia liked to say.
Recently, Evan had become colder. Passwords changed. Business meetings ran until midnight. He criticized groceries, baby clothes, even the electricity bill.
Meanwhile, he bought a $7,000 watch.
The cashier was pretending not to hear my conversation.
I looked at my daughter, Lily, rubbing her wet cheeks with tiny fists.
“Unfreeze the card.”
“No.”
“Evan.”
“You wanted to be a stay-at-home mother. Stay home.”
The line went dead.
I stood perfectly still.
Then I smiled.
Because Evan had forgotten something important.
Three years earlier, when Mercer Development nearly collapsed after a failed project, no bank would lend him another dollar. I had invested the inheritance my grandmother left me—$320,000—through a holding company created by my attorney.
In exchange, I received forty-nine percent ownership of Mercer Development and a secured lien against several company assets.
Evan knew about the investment.
He simply never bothered reading the paperwork.
He thought I had “helped him out.”
I thought about that as I opened a banking app he didn’t know I still used.
My grandmother’s trust account showed a balance large enough to buy every diaper in the store.
I paid with my personal debit card.
Then I called my attorney.
“Daniel,” I said, pushing Lily toward the exit, “I think it’s time.”
His voice sharpened immediately.
“Did something happen?”
“Yes.”
I glanced at the frozen credit card in my hand.
“My husband just reminded me exactly who he thinks owns everything.”
I dropped the card into a trash can.
“Let’s correct him.”
Part 2
When I arrived home, Patricia’s Mercedes was parked in my driveway.
Of course it was.
Inside, Evan sat at the kitchen island drinking bourbon while his mother flipped through property listings on a tablet.
Patricia looked up.
“Did you learn your lesson?”
I placed the diapers on the counter.
“What lesson?”
“That money doesn’t appear magically.”
I almost admired the confidence.
Evan swirled his glass. “I’ve created a monthly allowance for you. Two thousand dollars. Groceries, baby expenses, personal stuff. If you need more, ask.”
“You’re giving me an allowance?”
“You don’t earn anything.”
That sentence ended something inside me.
Not my marriage.
That had probably ended months earlier.
What ended was my hesitation.
I sat across from him.
“Are you sleeping with someone?”
His expression changed for half a second.
Patricia snapped, “Don’t be ridiculous.”
I looked only at Evan.
“Are you?”
He leaned back.
“What if I am?”
The cruelty was intentional.
He wanted me destabilized.
He wanted tears.
Instead, I nodded.
“Thank you.”
He frowned.
“For what?”
“For answering.”
That evening, Evan packed a suitcase and left for what he called a “business conference.”
He didn’t know I already had access to nearly six months of company expense reports because Mercer Development’s accounting platform still listed me as an authorized financial administrator.
I had never abused that access.
Now, with Daniel beside me, I reviewed records I was legally entitled to inspect as an owner.
Hotel suites.
Jewelry purchases.
Luxury dinners.
A monthly apartment lease downtown.
Nearly $84,000 in personal expenses charged to the company.
Then Daniel found something worse.
Evan had applied for a new commercial loan using equipment and property already covered by my secured agreement.
“He represented that the assets were unencumbered,” Daniel said.
I stared at the screen.
“He lied to the bank.”
“He appears to have.”
The next morning, we formally demanded company books and records.
Evan called within nine minutes.
“What the hell are you doing?”
“Reviewing my investment.”
“You don’t know anything about Mercer anymore.”
“I own forty-nine percent.”
Silence.
Then laughter.
“You own paper. I run the company.”
“That’s exactly what you should tell your attorney.”
He lowered his voice.
“Sarah, stop playing games.”
“I’m not.”
“You think because you put some inheritance money into the company years ago, you can threaten me?”
“No.”
I looked at the documents in front of me.
“I think the operating agreement can.”
That afternoon, Daniel notified the company’s lender of a potential conflict involving collateral. We did not accuse Evan of fraud. We provided the existing lien documents and requested clarification before any additional borrowing occurred.
The bank froze the pending loan.
By dinner, Patricia was calling me repeatedly.
I ignored her first six calls.
On the seventh, I answered.
“You vindictive little—”
“Careful.”
“You’re destroying your husband’s company!”
“No, Patricia. I’m checking whether my property is being illegally pledged.”
“You have no idea how business works.”
I smiled.
“I’m a CPA.”
She went silent.
Apparently Evan had never mentioned that part.
Then Daniel texted me another discovery.
Evan had scheduled an emergency board meeting for Friday.
His plan was obvious.
Force me out.
Dilute my ownership.
Make me powerless before I understood what was happening.
Unfortunately for Evan, he still hadn’t read the operating agreement.
Any new shares required unanimous approval.
Including mine.
He had targeted the one person who knew exactly how to follow the money.
Part 3
Friday morning, Evan walked into Mercer Development’s conference room looking confident enough to be photographed.
Patricia sat beside him.
So did Evan’s attorney, the CFO, and two senior managers.
I entered last with Daniel.
Evan smiled.
“Good. We can settle this.”
“I hope so.”
His attorney slid a folder toward me.
The proposal offered me $150,000 for my ownership interest.
Less than half of what I originally invested.
Evan folded his hands.
“You haven’t worked here in years. Take the money and focus on being a mother.”
Daniel glanced at me.
I opened the folder, read the first page, and closed it.
“No.”
Evan sighed theatrically.
“Sarah, don’t make this ugly.”
“You froze my credit card while I was buying diapers.”
Patricia rolled her eyes.
“Oh, please. Stop pretending this is about diapers.”
“She’s right,” I said.
Everyone looked at me.
“It isn’t.”
Daniel placed three binders on the table.
“The first contains documentation of Mrs. Mercer’s forty-nine-percent ownership. The second contains her secured-lending agreement and collateral schedule.”
Evan’s smile disappeared.
“And the third?” his attorney asked.
“Company expenditures requiring explanation.”
Daniel opened it.
The room went very quiet.
Evan leaned forward.
“Those are confidential.”
“To shareholders?” I asked.
His CFO stared at the pages.
“What is this apartment?”
Nobody answered.
I continued.
“Eighty-four thousand dollars in expenses. Hotels, jewelry, meals, rent. Were those legitimate business expenses?”
Evan stood.
“This meeting is over.”
“No,” his attorney said sharply. “Sit down.”
That was the moment Evan finally looked afraid.
Daniel explained that I was not demanding his arrest, his humiliation, or ownership of the entire company.
I wanted three things.
A forensic audit.
Repayment of unauthorized personal expenses.
And enforcement of the buy-sell provision triggered by financial misconduct affecting company assets.
Evan stared at his attorney.
“Tell her she can’t do that.”
His attorney did not answer immediately.
Then he said, “The agreement appears to allow it.”
Patricia shot to her feet.
“This company belongs to my son!”
The CFO finally spoke.
“Actually, it belongs to its shareholders.”
I almost laughed.
Evan turned toward me.
“You planned this.”
“No. You did.”
I leaned forward.
“You changed the passwords. Hid money. Used company funds for your affair. Tried to pledge collateral you didn’t fully control. Froze the household card because you wanted me dependent.”
His face reddened.
“And you thought that because I was home raising our daughter, I became stupid.”
Nobody moved.
I slid the frozen credit card across the table.
“You confused dependence with trust.”
The audit took seven weeks.
The results were worse than expected.
Evan had charged more than $126,000 in personal expenses to the company over two years. The bank terminated the pending financing application. Several managers demanded stronger financial controls.
Facing litigation, repayment obligations, and a forced ownership dispute he was unlikely to win cheaply, Evan agreed to settlement.
I bought his shares at a valuation reduced by documented debts and unauthorized withdrawals.
Patricia called me a thief.
I reminded her that thieves usually don’t come with audited spreadsheets.
Evan’s girlfriend disappeared two weeks after his company card stopped working.
That part felt almost poetic.
Eight months later, Mercer Development had a new CEO hired from outside the family.
I remained majority owner but returned only part-time as financial director.
More importantly, Lily and I moved into a sunny townhouse with a small garden.
One Saturday morning, I pushed her stroller through a grocery store.
She was nearly walking now, laughing at everything.
I reached the diaper aisle and remembered the humiliation of that frozen card.
My phone buzzed.
A message from Evan.
Can we talk? I’ve made mistakes.
I looked at Lily.
Then at the shelves in front of me.
I deleted the message.
At checkout, the cashier smiled.
“Credit or debit?”
I handed her my card.
“Mine,” I said.
And for the first time in years, that word felt exactly right.