PART 1 — THE CALL THAT CHANGED THANKSGIVING
My name is Richard Coleman, I’m seventy, and last Thanksgiving my daughter-in-law told me I was too poor to have an opinion in the house I had quietly helped them keep.
My son, Adam, and his wife, Vanessa, had invited me to dinner at their home outside Denver. I arrived with two pies and the bottle of bourbon Adam liked. Everything felt normal until Vanessa started complaining about the cost of groceries, utilities, and their mortgage.
I made one harmless suggestion.
“You might want to slow down on the renovations until the loan is smaller.”
Vanessa laughed.
“This house doesn’t run on your Social Security check, Richard. Maybe sit this course out.”
The table went quiet.
I looked at Adam.
He stared at his plate.
“Adam?”
He gave a tired shrug. “Dad, just let it go.”
That hurt more than Vanessa’s insult.
What neither of them seemed to remember was how they got that house.
Three years earlier, Adam’s construction business had nearly collapsed. His credit was damaged, Vanessa was pregnant, and their lender refused to approve the mortgage they wanted. I had sold my regional trucking company years before and lived simply, so everyone assumed my monthly Social Security check was most of what I had.
It wasn’t.
At Adam’s request, I placed $240,000 of my own money into a pledged investment account at their bank. That account served as additional security for a business-backed mortgage package and helped them qualify on favorable terms. The agreement was due for annual renewal the day after Thanksgiving.
I had renewed it twice without hesitation.
That night, I stood up from the table.
“Thanks for dinner.”
Adam finally looked at me. “You’re leaving?”
“Yes.”
Vanessa rolled her eyes. “Don’t be dramatic.”
I drove home without arguing.
At 9:20 the next morning, I called my banker, Ellen Parker.
“The collateral agreement renewing today,” I said. “I’m not signing it.”
She paused.
“Richard, if you decline, the bank will require Adam and Vanessa to replace the pledged collateral or restructure the loan.”
“I understand.”
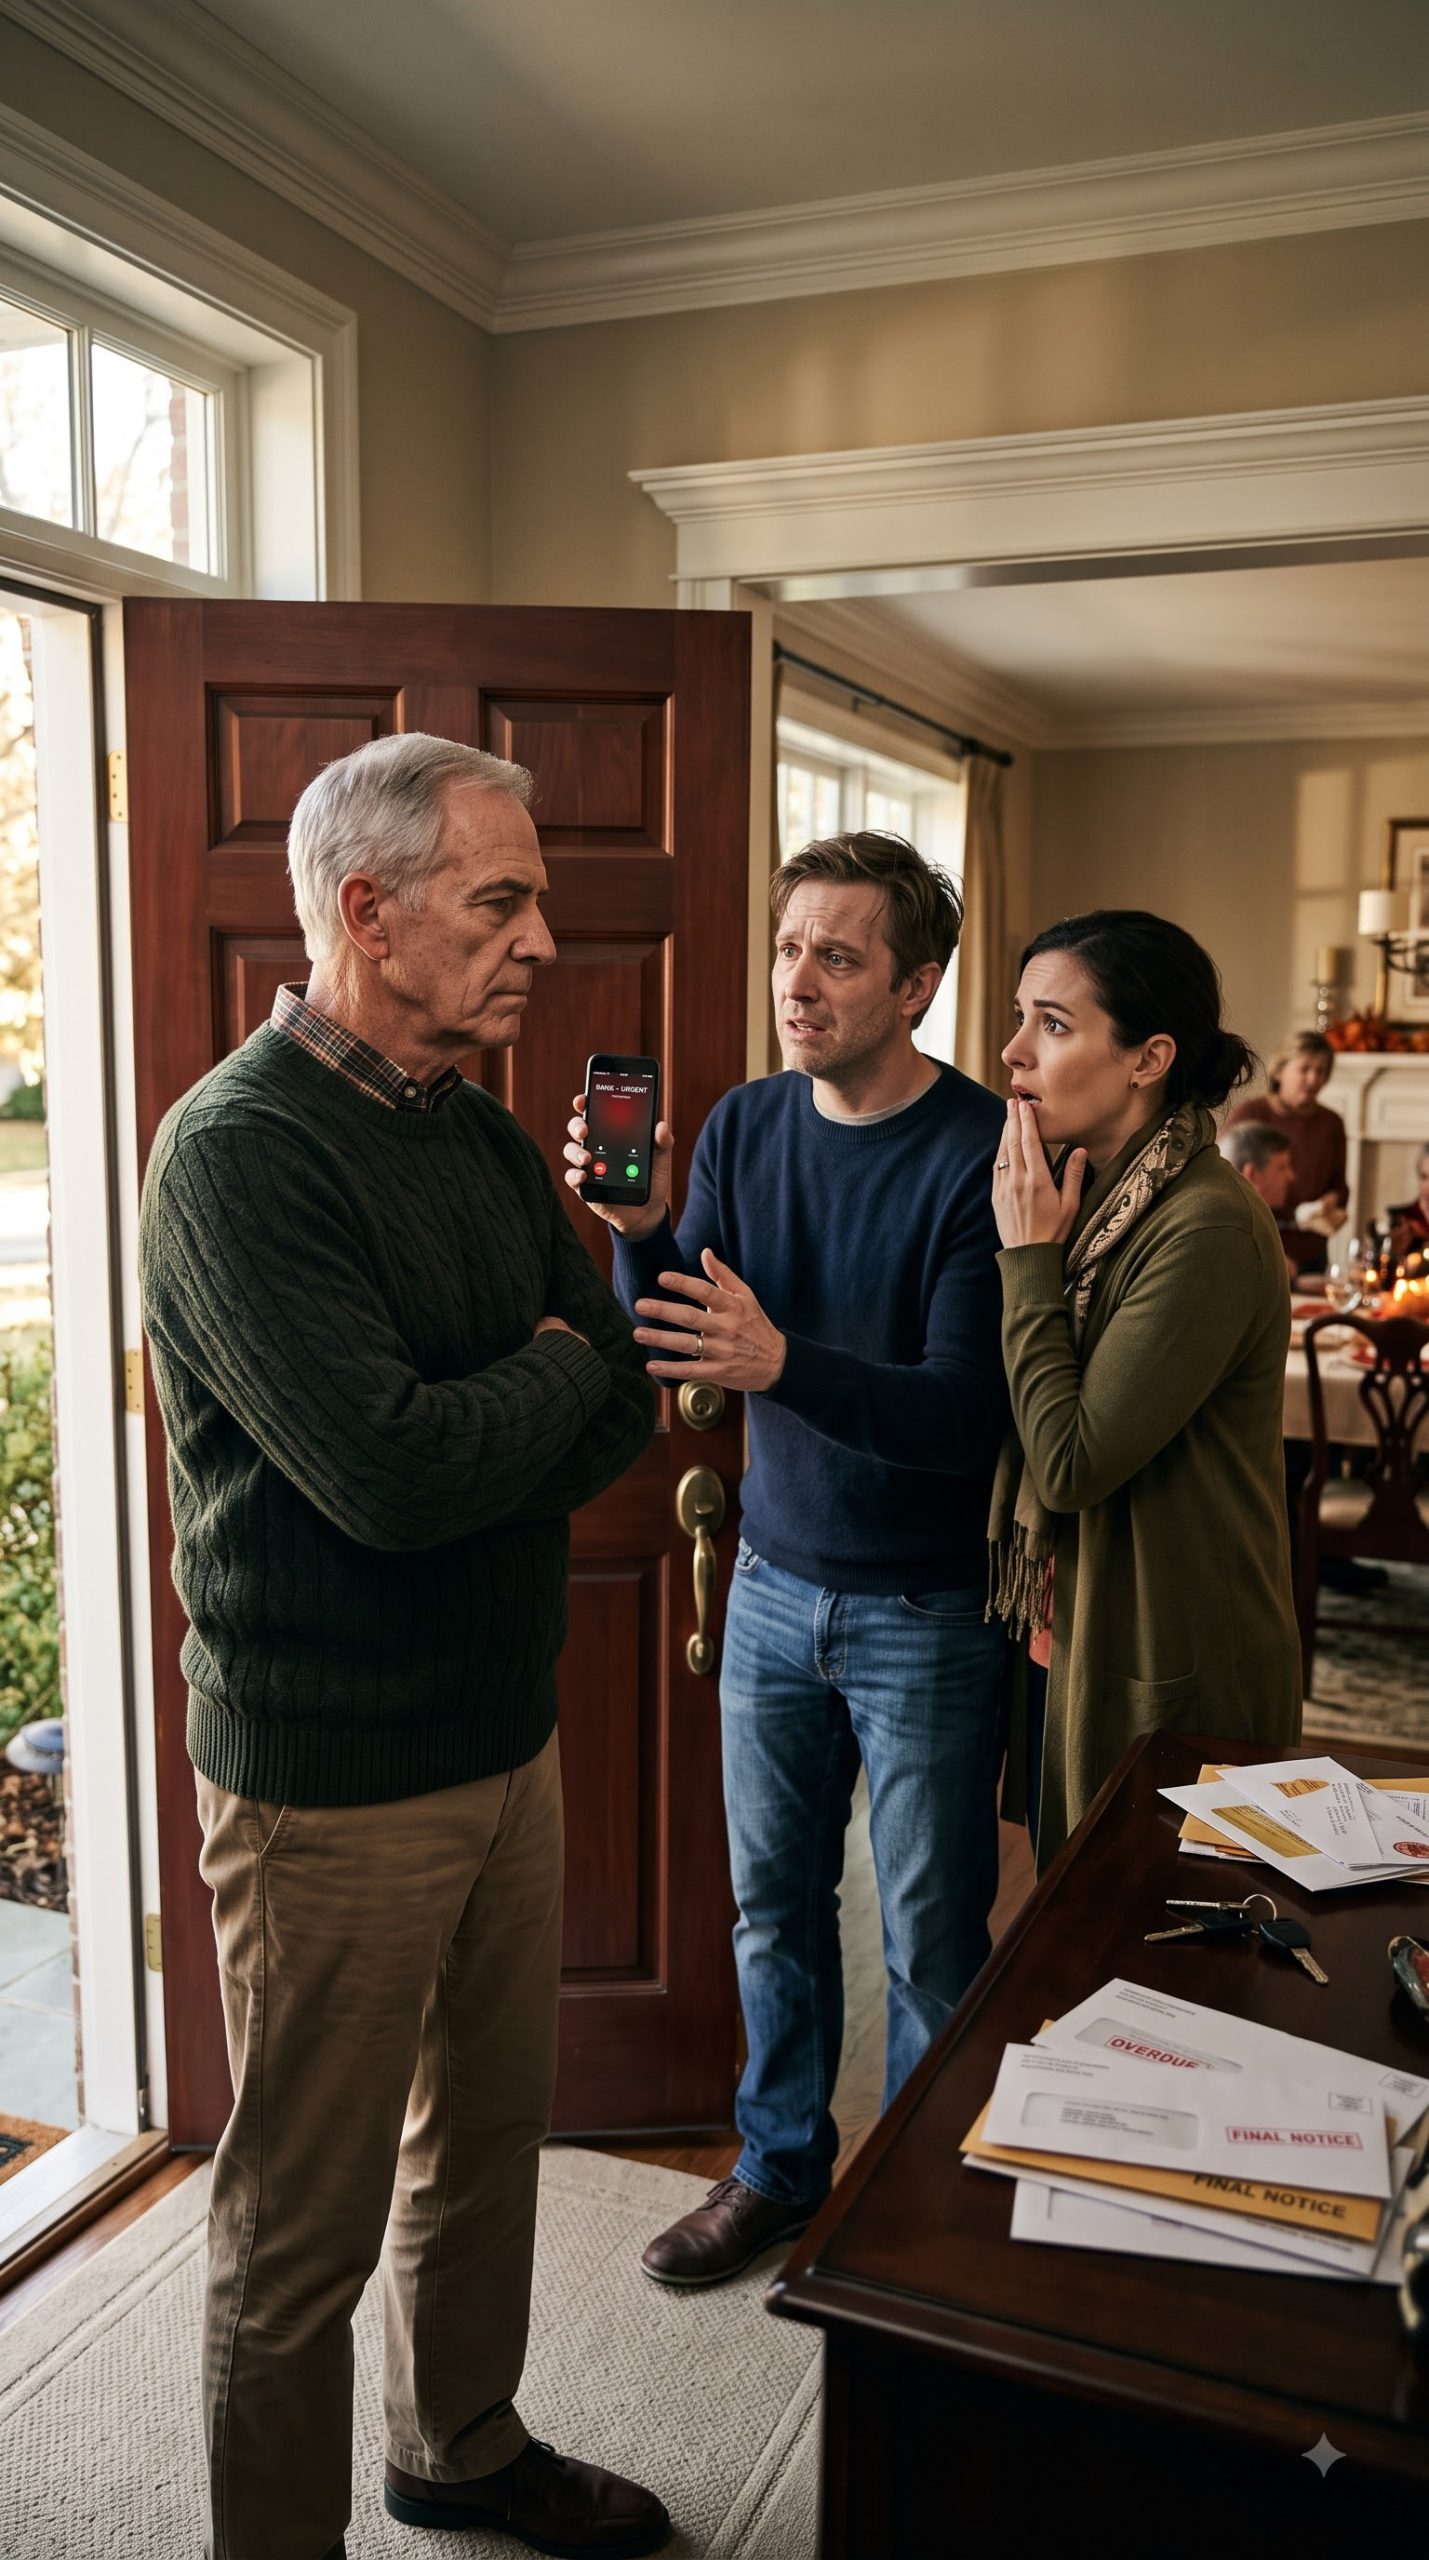
At 10:07, my doorbell started ringing.
Adam and Vanessa stood outside, both pale.
“Dad,” Adam shouted through the glass, “the bank just called. Please—undo this.”
PART 2 — WHEN THEY LEARNED WHAT I HAD REALLY BEEN PAYING FOR
I opened the door but didn’t invite them in.
Vanessa spoke first.
“You can’t do this because of one comment.”
“I didn’t do anything to your house,” I said. “I decided not to keep risking my money for it.”
Adam ran a hand through his hair.
“The bank says we have thirty days to replace the collateral or refinance part of the loan. We can’t qualify for that right now.”
“That sounds like something you should discuss with the bank.”
His face tightened.
“Dad, my business had a bad quarter. You know that.”
For months, Adam had told me everything was fine. Meanwhile, he and Vanessa had remodeled the kitchen, ordered custom patio doors, and leased a new SUV.
Vanessa crossed her arms.
“So this is punishment.”
“No. Punishment would be trying to hurt you. I’m simply no longer volunteering to protect you from financial risk while being treated like a useless old man.”
She stared at me.
“You were going to renew it before dinner.”
“Yes.”
“And now you won’t.”
“Yes.”
“That is punishment.”
I shook my head.
“It’s a consequence.”
Adam asked if we could sit down.
I let them into the kitchen.
He explained that his company had lost two contracts and was carrying more debt than he had admitted. Without my pledged account, the bank wanted a larger cash reserve or a partial paydown before renewing the loan package.
“How much?” I asked.
“About one hundred eighty thousand.”
Vanessa looked at me immediately.
That look told me exactly what she was thinking.
“You want me to write another check,” I said.
“No,” Adam replied quickly.
Vanessa didn’t.
She said, “It would solve everything.”
I looked at my son.
“That is exactly the problem.”
Adam lowered his eyes.
For years, every emergency had ended the same way. I paid. They thanked me. Then six months later, my help disappeared from their memory and became something they believed they had accomplished alone.
I told them I would meet with them and the bank on Monday, but I would not promise money.
At the meeting, Ellen laid out three options: sell some assets, refinance at a higher rate, or bring in new collateral from another source.
Vanessa asked, “What if Richard renews?”
Ellen looked at me.
I answered before she could.
“He won’t.”
Adam went silent.
Then Ellen slid a document across the table.
There was another problem.
Their business account had missed two covenant requirements, and Adam had personally guaranteed part of the debt.
For the first time, Vanessa turned toward her husband instead of me.
“You told me the company was fine.”
Adam’s face went pale.
And suddenly, Thanksgiving was no longer about my Social Security check.
PART 3 — THE DIFFERENCE BETWEEN HELP AND ENTITLEMENT
Adam’s construction company was struggling badly. He had hidden the numbers from Vanessa out of shame. Vanessa had kept spending because she believed the business was healthy. Both had built their lifestyle on the belief that I would always rescue them.
I refused to renew the $240,000 pledge.
But I didn’t abandon my son either.
I offered Adam something different: help from my accountant, introductions to two experienced business advisers, and money for a restructuring review. No blank check. No new guarantee.
He accepted.
Vanessa was furious at first.
“So you’ll pay accountants but not help your own family keep their home?”
I answered, “I’m helping you keep it. I’m just not buying your way out of every decision.”
Over the next three months, Adam sold two unused company vehicles, canceled plans for a second office, negotiated new terms with suppliers, and brought in a minority investor. Vanessa returned the leased SUV and delayed the rest of the remodeling.
They refinanced the mortgage at a higher rate without using my assets.
It hurt.
But it was theirs.
In February, Adam called and asked me to lunch.
“I owe you an apology,” he said.
“For Thanksgiving?”
“For more than Thanksgiving. I let Vanessa talk to you like your value was your monthly check, when I knew you had been the reason we got that house in the first place.”
I nodded.
Then he added, “I think I stayed quiet because admitting how much you helped me made me feel like I hadn’t made it on my own.”
That was harder to hear than anger, but more honest.
A week later, Vanessa came by too.
Her apology was awkward.
“I was disrespectful,” she said. “And I was wrong.”
I accepted it.
I didn’t restore the collateral.
By the next Thanksgiving, Adam and Vanessa were still in the same house. Dinner was smaller. No new renovations. No expensive wine.
When I walked in, Vanessa handed me the carving knife.
“Your house rules tonight, Richard.”
I laughed.
“No. Your house. Your responsibilities.”
I learned that helping your adult children can be generous, but helping them forever can make everyone forget where responsibility belongs. Sometimes the most loving thing you can do is stop being the financial safety net before resentment turns support into entitlement.
If your son stayed silent while his spouse mocked you after you had risked hundreds of thousands to help them, would you have renewed the guarantee anyway—or stepped back like I did?
Tell me what you would have done. I think a lot of American parents would disagree on where support ends and self-respect begins.