Part 1
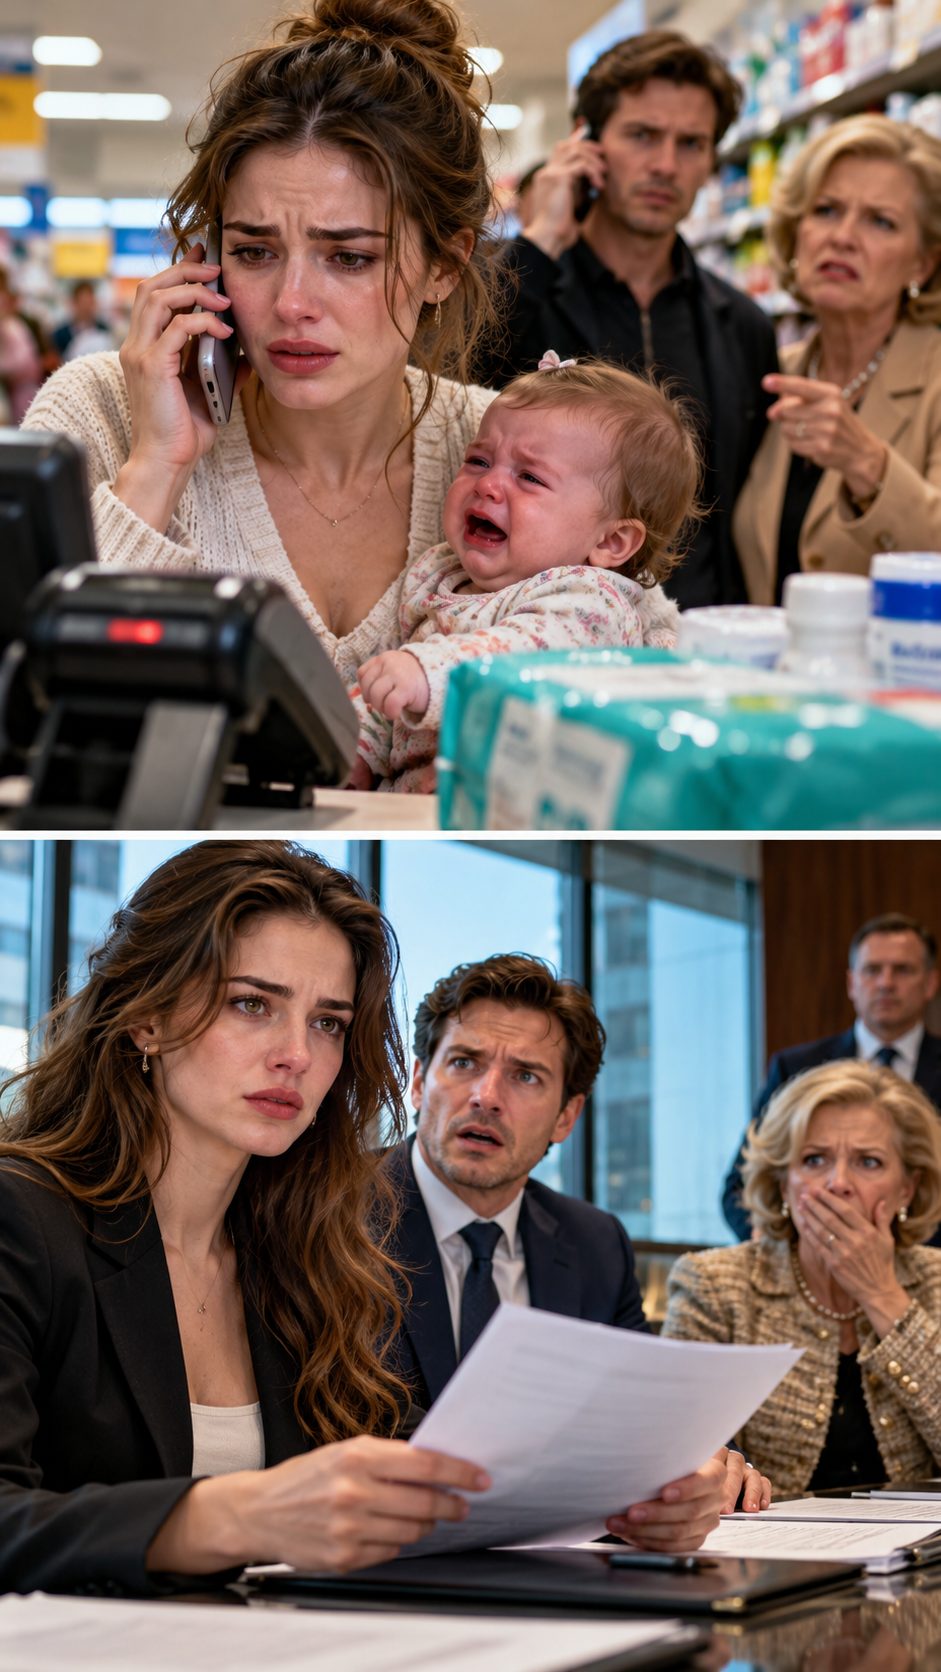
The cashier swiped my card twice before giving me the careful look people use when they think someone is about to break. Behind me, my six-month-old daughter cried in her stroller while the screen flashed DECLINED again.
I stared at the diapers and formula on the counter.
“Try it once more, please.”
Declined.
I called my husband, Ryan.
He answered over loud music.
“My card isn’t working,” I said. “I’m at the pharmacy. Sophie needs diapers.”
He sighed. “Not my problem. Figure it out yourself.”
I froze.
Then his mother, Diane, spoke near the phone. “Stop rescuing her, Ryan. She’s a useless leech. Maybe she should earn something for once.”
They laughed.
Not loudly. Casually.
That hurt more.
People in line began looking away. Heat climbed into my face. I had spent months measuring formula, washing bottles, scheduling pediatric visits, and stretching groceries so Ryan could keep saying his career required “focus.” Yet in one phone call, he and his mother reduced all of that work to dependency.
For a second, I wanted to cry right there.
Then I noticed something stranger than the insult: the missing money.
I ended the call.
The cashier whispered, “I can hold these for you.”
“No, thank you.”
I opened my banking app. My checking account showed $14.82. Our joint savings, which had held more than $38,000 two weeks earlier, showed $103. The credit card Ryan managed had been frozen.
For three years, he had insisted I stay home after Sophie was born because his consulting salary was “more than enough.” He called every dollar ours while keeping every important login under his control.
What Ryan didn’t know was that before I married him, I had co-founded a medical-software company and sold my stake.
I never hid the proceeds.
I protected them.
They sat in a premarital trust managed by a private bank. My father had taught me one rule: never confuse love with financial surrender.
I stepped away from the register and called Daniel Cho, my banker.
“Emily?” he answered.
“Release the funds.”
Silence.
“The reserve?”
“Yes. Move two hundred thousand into my personal account. Activate the emergency card. And send me every record of Ryan trying to access the trust.”
Daniel’s voice changed.
“He tried again this morning.”
My fear disappeared so quickly it surprised me.
“Again?”
“Second attempt this month. Both rejected.”
I looked at Sophie, hungry and red-faced.
“Send everything to my attorney.”
Within minutes, a digital card appeared on my phone. I paid for the diapers and formula.
Ryan thought he had cut me off.
He had no idea that by doing it, he had just activated the one plan I had prayed I would never need.
Part 2
When I got home, Ryan’s car was gone. On the kitchen island sat a note in Diane’s handwriting:
Since you refuse to contribute, Ryan will control household spending. You’ll receive an allowance when you learn responsibility.
I photographed it.
Ryan returned after midnight carrying restaurant leftovers.
“You figured out the diaper situation,” he said.
“I did.”
Diane entered behind him without knocking.
“We need boundaries,” she announced. “Ryan earns. You spend.”
I sat at the table with my laptop open.
Ryan smiled. “From now on, I approve purchases over fifty dollars. I’m also selling your car. Two vehicles are unnecessary.”
The car was mine, paid off before our marriage.
“Anything else?”
His smile widened. He mistook calm for surrender.
“No. I think you finally understand.”
The next morning, my attorney, Marissa, met me at a café with a thick folder.
Ryan had not merely drained our joint savings. Over four months, he had transferred $72,000 into an account controlled by Diane. He had also submitted two electronic requests attempting to link my premarital trust as collateral for a business loan.
Both contained signatures supposedly mine.
They weren’t.
Marissa tapped the forms. “The bank’s fraud team flagged them.”
My stomach tightened.
Ryan’s consulting company was failing. He had personally guaranteed debt, and Diane had been covering payments. Together, they had decided my trust would rescue them.
They never planned to ask.
They planned to corner me.
That afternoon, I moved Sophie and our essentials into a furnished apartment owned by my trust. I photographed everything I removed, left the rest untouched, and filed for legal separation.
Ryan called seventeen times.
I answered once.
“What did you do?” he shouted.
“I figured it out myself.”
“You can’t just leave.”
“I already did.”
“My mother says you’re stealing from me.”
“Your mother is holding seventy-two thousand dollars from our joint account. Be careful with that word.”
Silence.
Then: “You went through my accounts?”
“No. The bank did.”
He hung up.
Two hours later, Diane texted me.
You are destroying your family over money.
Then another arrived.
If you embarrass Ryan professionally, you’ll regret it.
I forwarded both to Marissa.
The next day, Ryan’s lawyer demanded access to “marital assets,” including my trust. Marissa answered with the trust agreement, bank records, and proof that the money predated our marriage.
His demand disappeared.
Marissa also obtained an order preventing either of us from selling major marital property while the case was pending. That meant Ryan could not touch the house, and he could not sell my car because he had threatened to. Every shortcut was closing.
Then Daniel found one more thing.
The first attempted trust authorization had been submitted from Ryan’s laptop.
The second came from Diane’s home network.
I stared at the report.
For years, they had treated me like the least powerful person in the room.
Now I knew exactly what they had done, exactly where the money went, and exactly how to prove it.
They had targeted the wrong woman.
Part 3
Three days later, Ryan and Diane entered the mediation room like they were attending my surrender.
My attorney sat beside me. Daniel appeared on a video call with the bank’s fraud representative.
Ryan stopped cold.
“What is this?”
“A financial disclosure meeting,” Marissa said.
Diane scoffed. “This is a family disagreement.”
“Some of it is a banking matter,” the representative replied.
Daniel displayed the records.
First, the $72,000 transferred from our joint savings into Diane’s account.
Then the attempted trust-access requests.
Then the digital signature logs, device records, IP addresses, and time stamps.
Ryan went pale. Diane stopped smiling.
“That proves nothing,” she snapped.
“It proves enough for the disputed funds to remain frozen during review,” Marissa said.
Diane stood. “You can’t freeze my money.”
“It isn’t your money,” I said.
“You called me useless because my card was declined while I was buying diapers. Then you drained our savings, cut off my access, tried to sell my car, and attempted to pledge my separate trust against Ryan’s debt.”
Ryan slammed his palm down. “I was trying to save our family.”
“No. You were trying to save yourself.”
“After everything I paid for?”
Marissa slid another folder across the table.
My trust had funded the down payment on our house through a documented separate-property contribution. It had also covered nearly $90,000 in household expenses while Ryan built his consulting business.
For years, he claimed he supported me.
The paperwork showed how much I had supported him.
After that, settlement talks moved quickly.
The disputed $72,000 was returned. The house was sold, my contribution was recognized before the remaining equity was divided under our agreement, and Ryan kept his business debts. I kept my trust, my car, and every account in my name.
The bank referred the forged authorizations for investigation. I cooperated and let the records speak.
Six months later, Ryan’s consulting company collapsed after creditors called his guarantees. Two clients left after learning he had misrepresented his finances.
I never contacted them. Consequences did not need my help.
A year later, I sat on my townhouse floor while Sophie built a crooked tower from wooden blocks.
I had returned to work part-time as an adviser to the company that acquired my startup. I chose my hours, controlled my money, and slept without fearing which account might vanish overnight.
Ryan saw Sophie according to the custody schedule. We communicated through a parenting app.
One afternoon, he sent a message:
I didn’t know you had that much money.
I typed:
That was never the problem.
My marriage had not ended over a declined card.
It ended when my husband heard that his baby needed diapers and decided humiliation was more useful than help.
I had not ruined him.
I had simply stopped protecting him from the consequences of what he chose to do.
Sophie knocked over her tower and laughed.
I laughed with her.
For the first time in years, nothing in my life depended on anyone’s permission.