PART 1: THE PRICE OF BEING THE GOOD DAUGHTER
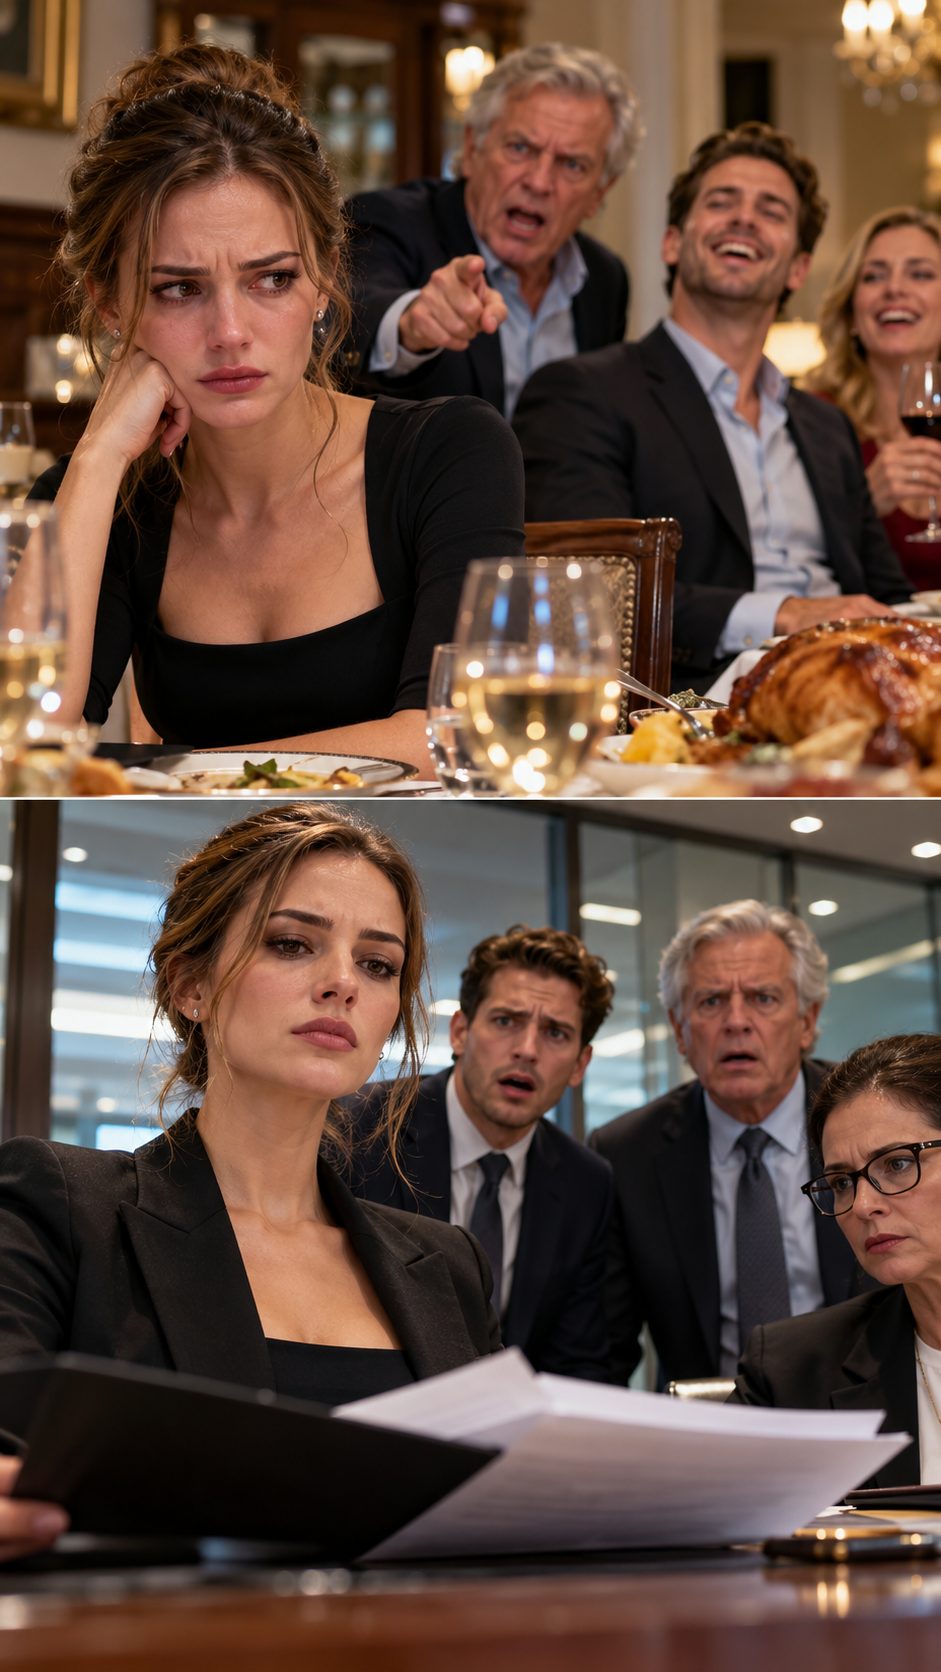
My father ordered me to surrender half my salary between the roast chicken and the mashed potatoes. My brother smiled like he’d just been handed the deed to my entire life.
“Starting next month,” Dad announced, setting down his wineglass, “half of your salary will go directly to your brother. He has a family to support, and you’re single.”
For three seconds, nobody spoke. Then my brother Ryan leaned back, grinning.
“Finally, you understand, Dad. It’s about time Emily started contributing.”
I stared at them across the dining table. My father, Richard Collins, was sixty-three, a retired businessman who believed being the head of the family meant owning everyone else’s decisions. Ryan, thirty-six, had inherited his arrogance but none of his work ethic.
I was thirty-three, a senior financial analyst earning $148,000 annually. I worked sixty-hour weeks, paid my mortgage, and had spent years cleaning up the financial disasters Ryan created.
Apparently, being responsible meant I had money to spare.
“Ryan has two children,” Dad continued. “You don’t. It’s only fair.”
Ryan’s wife, Melissa, smiled over her wineglass. “We could finally afford that bigger house.”
I almost laughed. They already lived in a four-bedroom home, drove luxury cars, and vacationed twice a year. Their problem wasn’t insufficient income. It was Ryan’s addiction to spending money he hadn’t earned.
“How much are we talking about?” Ryan asked eagerly.
“Half of whatever she takes home,” Dad replied.
“Wonderful. That should cover our new mortgage.”
They were discussing my paycheck as though I weren’t sitting there.
I picked up my napkin, folded it carefully, and placed it beside my plate.
“All right,” I said.
Dad blinked. “That’s it?”
I nodded. “I understand.”
Ryan laughed. “See? She knows family comes first.”
What neither man knew was that six weeks earlier, I’d discovered something devastating.
For years, I’d allowed my father limited financial authority through an old power-of-attorney document created when I underwent emergency surgery. I’d trusted him completely.
Then I noticed $42,000 missing from an account he’d been authorized to manage.
Investigating that withdrawal led me to something far worse: a $310,000 business credit agreement bearing my signature.
A signature I had never written.
Three days before dinner, my attorney had confirmed that someone had used my identity to guarantee Ryan’s failing construction business.
And Friday afternoon, we’d delivered evidence to the bank.
My father raised his glass.
“To family loyalty.”
I smiled and raised mine.
“To accountability.”
Neither man noticed the difference.
On Monday morning, they were planning to visit the bank.
So was I.
PART 2: THE SIGNATURE THEY SHOULD NEVER HAVE FORGED
Saturday morning, Ryan sent me a spreadsheet.
He had already calculated his monthly entitlement, including projected bonuses, overtime, and annual raises.
At the bottom, he’d written: Family contribution. Mandatory.
An hour later, Melissa sent me photographs of a six-bedroom house.
“This is what your help will make possible!” she wrote.
I forwarded everything to my attorney, Victoria Hayes.
Her response came immediately.
“Keep every message. They’re getting careless.”
Victoria had spent fifteen years handling financial fraud litigation. When I’d first brought her the suspicious credit agreement, she hadn’t promised revenge. She’d promised evidence.
And the evidence was considerably worse than either of us expected.
The $310,000 credit facility belonged to Collins Construction, the struggling business my father had started and Ryan now managed. According to the lender’s records, I’d personally guaranteed its obligations.
But the signature was copied from a document I’d signed years earlier.
The email address used during the application wasn’t mine. The supporting financial statements overstated the company’s revenue. Worse, the application contained an outdated asset statement showing a property I’d sold eighteen months before.
Someone had apparently assumed the bank would never verify those details.
“Can they make me pay?” I’d asked Victoria.
“They can try to enforce the guarantee until we establish what happened,” she’d explained. “But we have powerful evidence that you never agreed to it.”
Our independent accountant had uncovered another disturbing pattern.
Ryan’s company had paid nearly $180,000 to a consulting business registered to Melissa. The invoices described project-management services, but the records we’d obtained showed little evidence that those services existed.
Meanwhile, subcontractors were threatening legal action over unpaid bills.
My brother wasn’t struggling to support his family.
He was draining his own business.
By Friday, Victoria had submitted my sworn fraud statement, a formal revocation of my father’s financial authority, and supporting documentation to the bank.
The lender had acknowledged receipt and placed further advances under review.
Ryan knew none of this.
Sunday afternoon, Dad called.
“Your brother has arranged an appointment with Northwood Bank tomorrow. We’re setting up the transfers and discussing his business credit.”
“Sounds important.”
“You don’t need to come. I still have your authorization paperwork.”
I looked at the fresh revocation confirmation on my desk.
“Are you sure about that?”
His voice hardened. “Don’t start questioning me, Emily. I raised you.”
Then Ryan grabbed the phone.
“Just enjoy your little apartment and your single life. Some of us have actual responsibilities.”
I glanced around my spacious, mortgage-free condominium.
“You’re right,” I said softly. “Tomorrow will be very educational.”
He laughed before hanging up.
Ten minutes later, Victoria called.
“The bank confirmed the nine o’clock meeting. They’ve agreed to review the disputed credit documents with counsel present.”
“And the investigation?”
“Still ongoing. But your personal accounts are protected, and your father no longer has authority to operate them.”
I closed my eyes.
For years, I’d mistaken obedience for love.
I’d paid Ryan’s car installments, covered Dad’s property taxes, and rescued the company whenever cash disappeared.
Every sacrifice had taught them the same lesson: Emily would always surrender.
This time, I’d changed the lesson.
And Monday morning, they were about to discover that the daughter they considered their personal bank account had finally closed the branch.
PART 3: THE BANK MANAGER’S QUESTION
Monday morning, my father and Ryan walked into Northwood Bank wearing matching expressions of confidence.
Ryan carried a leather briefcase. Dad carried the old power-of-attorney document.
Branch manager Patricia Bennett greeted them and opened their account file.
“We’d like to establish a monthly transfer from my daughter’s account,” Dad announced. “And my son needs additional funds from his business credit line.”
Patricia studied her computer screen.
Then she looked up.
“Didn’t she tell you?”
Dad frowned. “Tell me what?”
“Your daughter revoked your financial authorization on Friday. You no longer have permission to access or manage her accounts.”
Ryan stopped smiling.
“That’s impossible,” Dad snapped. “I’m her father!”
“That doesn’t give you legal authority over her finances, Mr. Collins.”
He slapped the paperwork onto her desk.
“This document says otherwise!”
“That authority has been revoked, sir.”
Ryan leaned forward. “Fine. Forget her salary for now. We need another fifty thousand from the company credit line.”
Patricia’s expression hardened.
“Further advances have been suspended pending investigation of irregularities in the lending documents.”
Dad turned pale.
“What irregularities?”
That was when I entered the conference room with Victoria.
“Hello, Dad.”
Ryan stood so suddenly his chair scraped backward.
“What are you doing here?”
“Protecting what belongs to me.”
Victoria placed a thick folder on the table.
“The bank has received evidence that Emily’s signature was forged on the personal guarantee. We’ve also formally disputed the unauthorized transactions from her account.”
Dad stared at the documents.
Then he made his fatal mistake.
“We were going to pay everything back!”
The room went silent.
Victoria calmly wrote down his exact words.
Ryan grabbed his briefcase.
“This is ridiculous. We’re leaving.”
“You’re free to leave,” Patricia replied. “But the lending investigation will continue.”
Six months later, the consequences were undeniable.
The bank’s investigation confirmed that my signature had been fraudulently used. My disputed guarantee was released, and the lender pursued the business and the people responsible for its debts.
Further investigation uncovered false financial statements and payments to Melissa’s company that couldn’t be justified.
Ryan was charged with loan fraud and forgery. He eventually pleaded guilty and received a custodial sentence and restitution order.
Dad admitted his involvement in the fraudulent application. His plea agreement included probation and substantial restitution.
Collins Construction collapsed under its debts. Dad sold his vacation property to help satisfy the judgment. Melissa divorced Ryan after the family’s finances unraveled.
I received a partial recovery of the money misappropriated from my account through a civil settlement.
Dad called me once.
“You destroyed this family.”
I looked out over the ocean from the balcony of my new home.
“No, Dad. You tried to sell your daughter’s future to finance your son’s mistakes.”
He started crying.
For the first time, I didn’t rush to comfort him.
A year later, I was promoted to financial director. My savings were growing, my friendships were stronger, and every account I owned was mine alone.
One Sunday evening, I made dinner for people who loved me without expecting payment.
There were no demands, no threats, and no arguments about who deserved my paycheck.
Only laughter and peace.
My father had once declared that half my salary belonged to my brother because I was single.
He’d been wrong about something much bigger.
My money had never belonged to them.
And neither had I.