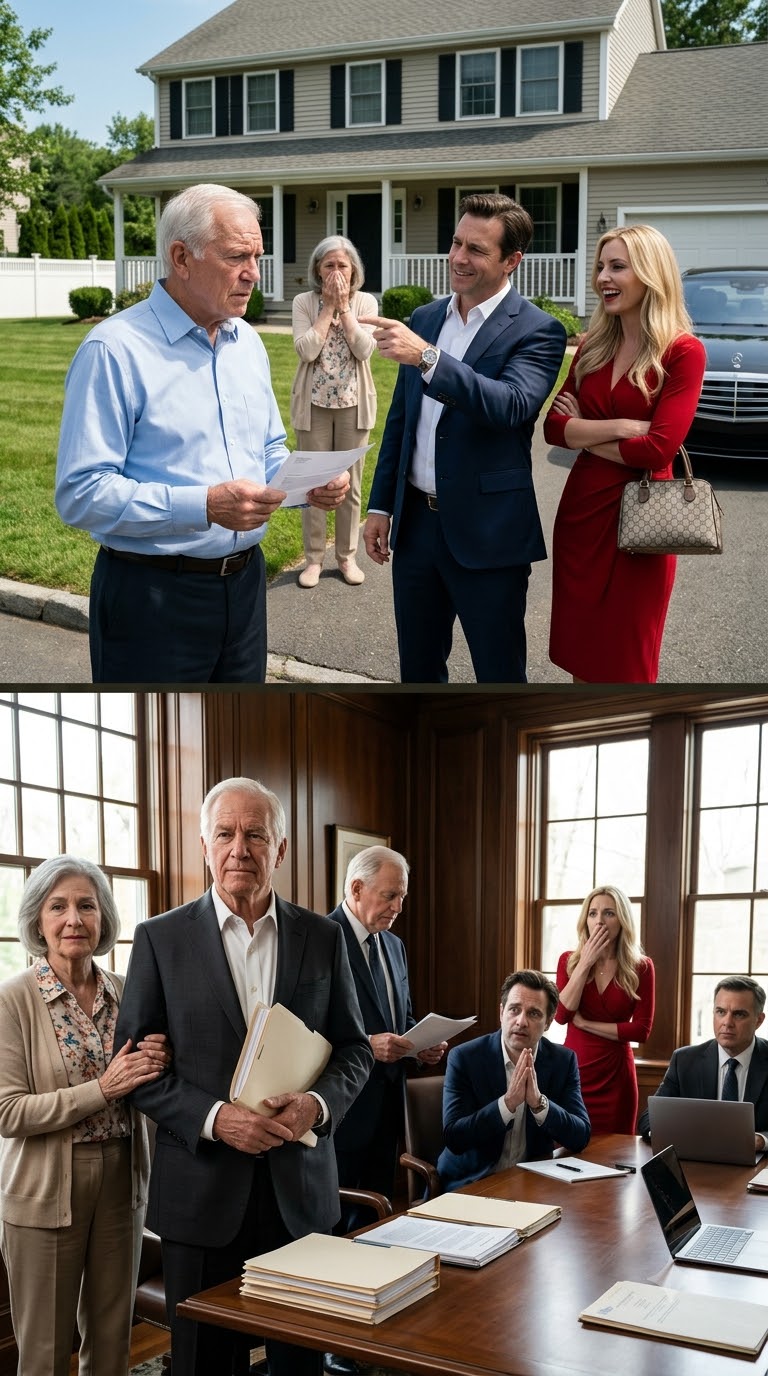
“Social Security is enough for you and Mom. We need more,” my son sneered, standing in the front yard of the home I’d spent forty years paying for. Then he casually announced that a bank appraiser would be coming to inspect my property—a property I had never agreed to sell, refinance, or surrender.
My name is Thomas Whitaker. I’m seventy-three years old, and until that afternoon, I believed my greatest accomplishment was raising a decent son.
I was wrong.
My wife, Margaret, and I bought our little colonial house in Connecticut in 1982. Back then, we couldn’t afford curtains. We ate dinner on folding chairs while I worked double shifts at an electrical company.
Forty-four years later, the mortgage was gone.
The house was worth nearly nine hundred thousand dollars.
And apparently, my son had already decided what to do with it.
His name was Brian. Forty-one years old, expensive suits, luxury vehicles, and a wife named Vanessa who considered anything less than first class an insult.
That afternoon, Brian arrived carrying an envelope from Harbor State Bank.
“Dad, this is just routine paperwork,” he said.
I opened it.
Inside was a notice concerning a preliminary home-equity loan application.
“Brian, why is the bank contacting me?”
He laughed.
“Relax. Vanessa and I are expanding our investment business. We’re using the house as collateral.”
I looked up slowly.
“Whose house?”
He rolled his eyes.
“Come on, Dad. You’re getting old. Eventually, everything comes to me anyway.”
Margaret stood behind the screen door, her hands trembling.
“Brian,” she whispered, “that’s our home.”
He shrugged.
“You two have Social Security. What else do you need?”
The words struck harder than any physical blow.
Then Vanessa stepped out of their Mercedes.
“We’re talking about family wealth, Thomas. Don’t be selfish.”
I folded the bank letter.
“Did you submit this application without asking us?”
Brian smirked.
“An appraiser will be here Thursday. Just cooperate.”
They drove away laughing.
Margaret started crying.
I held her close.
“Are we going to lose our house?” she asked.
“No, sweetheart.”
But I didn’t tell her why I was so certain.
Twenty years earlier, I’d watched my younger brother lose everything after trusting the wrong business partner.
Afterward, Margaret and I had made arrangements specifically designed to prevent anyone from taking our home through manipulation.
Brian knew almost nothing about those arrangements.
I went inside, retrieved an old leather address book, and called our former attorney.
“Daniel,” I said, “someone is trying to borrow money against my house.”
“Who?”
I stared at the photograph of Brian on his wedding day.
“My son.”
PART 2
Daniel Mercer arrived the following morning.
He was seventy himself, but his mind remained sharp.
I handed him the bank letter.
He read it twice.
“Thomas, have you signed anything recently?”
“No.”
“Have you given Brian financial power of attorney?”
“Absolutely not.”
Daniel studied the account reference number.
“Then we need to contact this lender immediately.”
We drove to Harbor State Bank and met with its fraud investigations manager.
After verifying our identities, we learned that a loan application for three hundred and twenty thousand dollars had been submitted using my name.
Brian was listed as an authorized representative.
The application included income information, property details, and a document purporting to give him authority to act for me.
Daniel requested that the bank preserve all records and prevent further processing while ownership and authorization were investigated.
Then the manager showed us a copy of the supposed authorization.
My signature appeared at the bottom.
Except I hadn’t written it.
I recognized the shape immediately.
Someone had copied my signature from an old insurance form, including a peculiar bend in the final letter caused by an injured finger.
My hands turned cold.
“He forged it,” I whispered.
Daniel leaned forward.
“We’ll need a proper examination, but this is serious.”
Then the manager revealed something worse.
The loan proceeds were intended for a company called Whitaker Development Holdings.
Brian had told the bank he controlled the property through a family arrangement.
He hadn’t merely expected an inheritance.
He was trying to turn our home into cash.
When we returned, Daniel opened the trust documents Margaret and I had signed years earlier.
Our house was held in a revocable living trust. Margaret and I were the acting trustees, and major transactions involving the property required both our approval under its terms.
Brian was only a successor trustee, with no present authority.
The lender hadn’t approved the loan, and the paperwork Brian submitted could not give him ownership.
Daniel smiled grimly.
“Your son has targeted an asset he doesn’t legally control.”
That afternoon, Brian called.
“Dad, why did the bank put everything on hold?”
“I asked them to verify the application.”
He exploded.
“You’re embarrassing me! My investors are waiting!”
“Then explain why you submitted my signature.”
Silence.
Finally, he snapped, “Vanessa handled the documents!”
I recorded his exact words in my notes after the call.
Daniel helped us file a police report and notify the bank’s fraud department in writing. We also obtained updated land records confirming the trust’s ownership.
Meanwhile, a financial consultant familiar with Brian’s business contacted Daniel after receiving the bank’s verification request.
Brian had already promised investors that the loan money would cover overdue obligations.
His business wasn’t expanding.
It was collapsing.
And our home was supposed to rescue it.
That evening, Vanessa sent Margaret a vicious message.
Stop letting Thomas ruin Brian’s future. You’ll both be dead before you ever need that house.
Margaret read it and began shaking.
I took her hand.
“Keep that message.”
“Why?”
“Because people who believe they’re untouchable eventually explain themselves in writing.”
On the fifth day, Daniel received copies of additional transaction records through our authorized request to the lender.
They linked the disputed application to Brian’s business email and identified Vanessa as a document contact.
Daniel laid the evidence across his desk.
“Thomas, tomorrow we give them one opportunity to explain.”
I looked at the forged signature.
“Good. But this time, we’re choosing the meeting place.”
PART 3
On the sixth morning, Brian and Vanessa entered Daniel’s conference room expecting another family argument.
Instead, they found a bank representative, my attorney, Margaret, and me waiting beside two thick folders.
Brian laughed nervously.
“Dad, what is this? Some kind of intervention?”
Daniel gestured toward the chairs.
“Please sit.”
Vanessa folded her arms.
“We don’t have time for theatrics.”
I pushed the loan application across the table.
“Brian, is this your submission?”
He glanced at it.
“Yes. And?”
“Is that my signature?”
He hesitated.
“Obviously.”
I placed the original insurance document beside it.
“Then explain why the signatures contain exactly the same unusual pen marks.”
His face changed.
Vanessa looked toward the door.
Daniel spoke calmly.
“The bank has suspended the application. The property records confirm that neither of you has authority to encumber the home. We’ve also filed a report concerning suspected document forgery and attempted financial fraud.”
Brian shot to his feet.
“You called the police on your own son?”
“No,” I answered. “I reported what happened. You’re responsible for your choices.”
Vanessa pointed at Margaret.
“She barely understands what’s going on!”
My wife stood.
For forty-seven years, Margaret had been the gentlest person I knew.
But her voice was steady.
“I understand perfectly. You wanted to put our house at risk so you could pay your debts.”
Vanessa went pale.
Brian turned toward her.
“You told me the trust wouldn’t matter!”
Silence filled the room.
Then he whispered, “You said Dad had already agreed.”
Vanessa couldn’t answer.
Daniel opened the second folder.
It contained financial records showing the lender had been given misleading information about the property.
“The bank will make its own decisions about further action,” he explained. “Our clients will not authorize this loan or guarantee your company’s debts.”
Brian looked at me desperately.
“Dad, if this funding disappears, my business is finished.”
“Then you should have told me the truth.”
“Please! I’ll lose everything!”
I remembered the years Margaret worked nights, the birthday parties we’d missed, and the mortgage payments we made when money was painfully tight.
“You were willing to gamble away the only home your mother has ever loved.”
His eyes filled with tears.
“I made a mistake.”
“No, Brian. A mistake is forgetting an appointment. This required paperwork, planning, and lying.”
Vanessa grabbed her handbag and stormed out.
Brian remained sitting, staring at the table.
I didn’t celebrate.
I simply walked Margaret to our car.
Over the following months, Brian’s investment company entered bankruptcy proceedings after its creditors demanded payment.
Investigators reviewed the disputed loan documents. Brian eventually accepted responsibility in a negotiated criminal case involving attempted financial fraud and received supervised probation, restitution obligations, and a substantial fine.
Vanessa separated from him as their expensive lifestyle collapsed.
Their luxury home was sold, and Brian moved into a small rented apartment.
Our house remained untouched.
Six months later, Margaret and I sat on our front porch watching the sun disappear behind the maple trees.
We had installed new garden lights, replaced the old fence, and finally booked the anniversary trip we’d postponed for years.
Brian had written several letters apologizing.
I answered one.
I told him forgiveness might come someday, but access to our finances never would.
Margaret leaned against my shoulder.
“Do you think we were too harsh?”
I looked at the home we’d built our lives around.
“No. We protected what we worked for.”
She smiled.
Inside, the clock chimed six.
Our dinner was ready, our bills were paid, and no one could take our peace without our consent.
My son had believed Social Security was enough for us because he thought everything else already belonged to him.
He’d forgotten something important.
An inheritance is not an entitlement. And growing old doesn’t mean surrendering the right to say no.