My name is Harold Mitchell. I’m sixty-nine years old, and that afternoon, I learned exactly how much my family valued me.
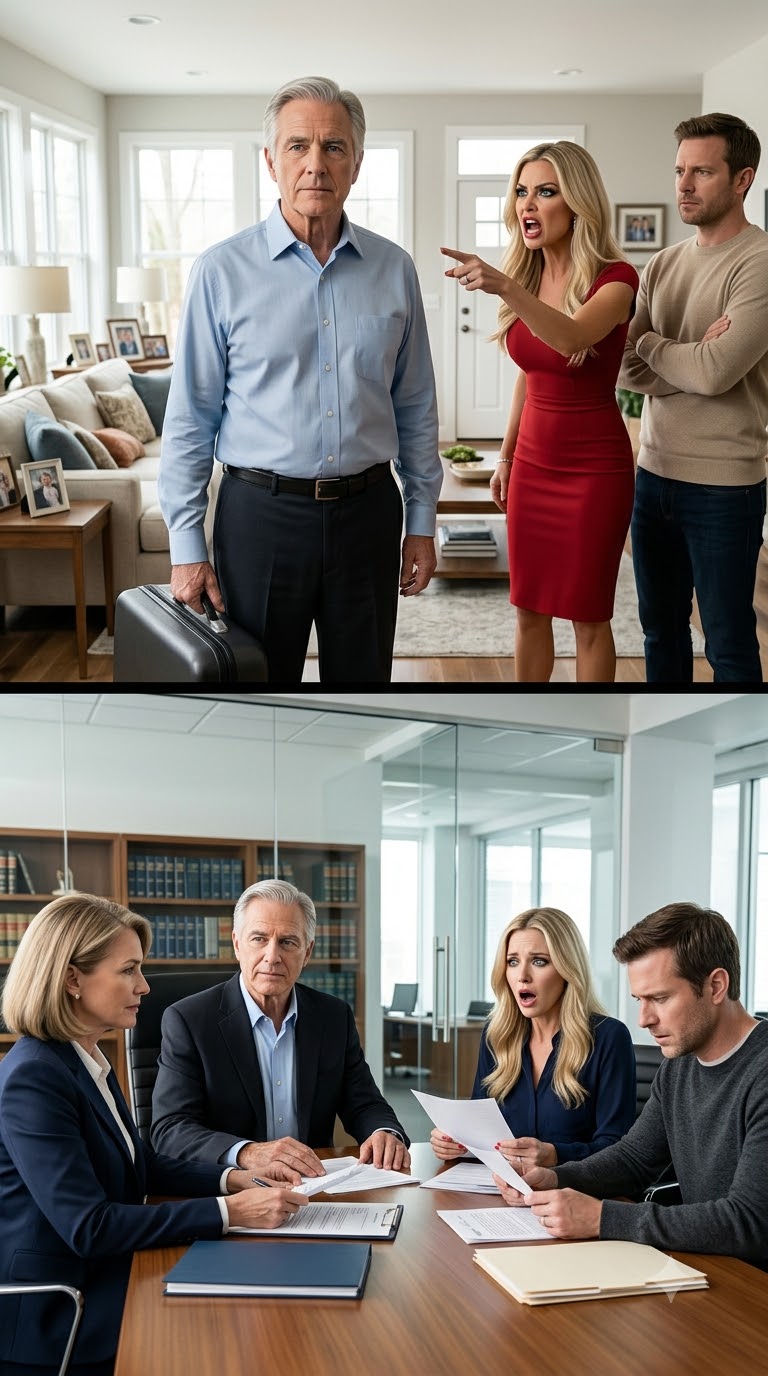
“Dad, Melissa’s right,” my son Brian said. “You’ve overstayed your welcome.”
I stared at him.
“Brian, I paid for this house.”
Melissa burst out laughing.
“You helped with the down payment! That doesn’t mean you own us!”
Six months earlier, Brian had begged me for help purchasing a beautiful suburban home.
His credit was terrible. Melissa had expensive tastes, and they’d accumulated enormous debts.
I agreed to help, but their lender refused to approve them.
So I purchased the property through my family investment company and signed a lease giving them an option to buy it later.
They paid rent into a dedicated property account.
At least, they were supposed to.
For four months, no payment had arrived.
Instead, Melissa had ordered designer furniture and booked an expensive anniversary vacation.
When I gently reminded Brian about the missed payments, she exploded.
“You’re obsessed with money! We don’t owe you anything!”
I looked around the living room.
I’d repaired the kitchen, landscaped the garden, and spent countless weekends helping them move.
Now they were throwing me out of the guest bedroom where I’d been staying during renovations to my own apartment.
Brian crossed his arms.
“Melissa says you’re making her uncomfortable. We want you gone.”
I waited for him to apologize.
He didn’t.
Melissa pointed toward the door.
“And don’t come crawling back when you run out of money!”
I smiled faintly.
“Don’t worry. I won’t.”
She sneered.
“You’ll probably end up begging outside a grocery store.”
I picked up my suitcase and walked outside.
They didn’t know I’d spent forty years managing commercial properties.
They didn’t know my retirement investments exceeded $800,000.
And most importantly, they hadn’t read the purchase option agreement they’d signed.
It required them to remain current on rent, meet a financing deadline, and reimburse specific approved property expenses before exercising their option.
They’d violated nearly every requirement.
That evening, I called my attorney, Susan Blake.
“Harold, are you finally ready to enforce the contract?”
I looked at the photograph of my late wife resting beside my suitcase.
“Yes,” I answered.
“But first, I want a complete accounting.”
Melissa thought she’d thrown a helpless old man into the street.
She had actually thrown away the only person keeping her luxurious lifestyle afloat.
Part 2
Susan called the following morning.
“The property account is more complicated than we expected.”
I sat upright.
“What happened?”
“Brian has been telling Melissa the house belongs to him. He’s also been telling their bank that the purchase is already complete.”
I stared at the wall.
“That’s impossible. The deed is held by Mitchell Property Holdings.”
“Exactly. But they’ve been using an anticipated inheritance and nonexistent home equity to support new credit applications.”
Susan emailed me copies of the documents obtained during our review.
One application listed a $300,000 ownership interest Brian didn’t possess.
Another showed a forged letter supposedly confirming that I had transferred the property to him.
My hands went cold.
I recognized my signature.
I hadn’t written it.
Susan instructed me to preserve everything while she contacted the lender and requested a formal investigation.
Meanwhile, Brian called.
“Dad, Melissa says you embarrassed her. You should apologize.”
“For asking about unpaid rent?”
“You’re making everything about money!”
“Brian, have you been telling lenders you own the house?”
Silence.
Then he snapped.
“It’s going to be mine eventually!”
“That isn’t what I asked.”
He hung up.
The following week, an independent accountant completed the property review.
Brian and Melissa owed more than $26,000 in rent and reimbursable expenses. They had also provided misleading financial information during their attempted purchase.
But one discovery was especially important.
Months earlier, Brian had voluntarily placed $74,000 into a purchase escrow account administered by the closing company.
Those funds were intended for the eventual purchase, not available for personal spending.
The signed agreement specifically permitted documented overdue contractual amounts to be deducted from the escrow, with the remainder returned if the purchase failed.
Susan looked at me.
“We can terminate their option if the contractual default isn’t cured after proper notice. Then the closing agent can reconcile the escrow according to the agreement.”
“Do everything by the book,” I said.
We delivered the required notices through the proper channels.
Brian ignored them.
Melissa posted photographs of their upcoming vacation and wrote proudly about becoming homeowners.
Three days before the cure deadline, she called me.
“We’re replacing the locks. You’re not welcome here anymore.”
“Melissa, I own the property.”
She laughed.
“Not for much longer! Brian’s buying it, and you can’t stop us.”
“Have you spoken to the closing agent?”
“Why would I? Everything’s already arranged.”
I almost felt sorry for her.
Almost.
The deadline passed without payment or a valid financing commitment.
Susan confirmed that the purchase option had expired under its terms.
The property remained mine.
Then the closing agent issued the final escrow accounting, deducting the documented contractual charges and arranging the return of the balance to Brian.
At the same time, the lender froze Brian’s pending credit application over the disputed ownership documents.
Their imagined fortune had vanished.
Three weeks after throwing me out, they discovered their home purchase was dead.
And Melissa made a frantic phone call that changed everything.
Part 3
“YOU STOLE OUR MONEY!” Melissa screamed through the telephone. “OUR ACCOUNT IS EMPTY!”
I was sitting on my apartment balcony, drinking coffee.
“Which account?”
“THE HOUSE ACCOUNT! SEVENTY-FOUR THOUSAND DOLLARS!”
“The purchase escrow?”
“Don’t play stupid, Harold!”
I set down my cup.
“That money was governed by your signed agreement. The closing agent has already sent the final statement.”
Brian grabbed the phone.
“Dad, what have you done?”
“I enforced the contract.”
“You can’t take our house!”
“Brian, it was never your house.”
Two hours later, they arrived at Susan’s office.
Melissa stormed inside, waving bank statements.
“You drained our account!”
Susan remained perfectly calm.
“No personal bank account was accessed. The escrow agent distributed funds under the agreement you signed. The remaining balance is being returned to Brian’s designated account.”
Melissa froze.
“What about our mortgage?”
“The lender suspended your application after discovering inconsistent ownership information.”
Brian sank into a chair.
Susan placed three documents on the table.
The recorded deed.
The signed purchase option.
The final escrow accounting.
“Your option expired after the notice period,” she explained. “You failed to cure the defaults and did not secure financing.”
Melissa pointed at me.
“You planned this!”
I shook my head.
“I planned to help my son buy a home. You planned to live in it without honoring your obligations.”
Brian stared at the documents.
“Dad, please. Give us another chance.”
“Did you forge my signature?”
His face turned pale.
Melissa looked at him.
“Brian?”
He whispered, “I thought he’d transfer it eventually.”
Susan spoke firmly.
“The disputed document has been referred to the lender’s fraud department. You should obtain independent legal advice.”
Melissa began crying.
“Our lives are ruined!”
I looked at her.
“Three weeks ago, you told me I’d end up begging on the street. Today, you’re asking me to ignore a contract you both signed.”
Neither answered.
I didn’t throw them out that afternoon. My attorney followed the required legal process to recover possession after their tenancy ended.
They eventually agreed to vacate under a court-approved settlement, avoiding further litigation over possession.
Their damaged credit and unpaid personal debts forced them into a small rental apartment.
Brian’s employer also investigated the false financial documents after they became relevant to a background review for a promotion. He lost the opportunity.
Six months later, I sold the house to an unrelated buyer.
The proceeds went into my retirement portfolio, alongside the $800,000 I’d quietly saved throughout my working life.
I purchased a peaceful lakeside cottage and began volunteering at a community housing charity.
One Sunday, Brian visited.
He looked exhausted.
“Dad, I treated you terribly.”
I waited.
“I knew the house wasn’t mine. I was afraid Melissa would leave if she discovered how much debt we had.”
“Then you should have told her the truth.”
He lowered his head.
“I know.”
I didn’t offer him money.
But I offered something more difficult.
A chance to rebuild our relationship through honesty.
After he left, I sat beside the lake watching sunlight dance across the water.
Melissa had called me a useless old man.
She’d assumed that because I dressed simply, I had nothing.
But I had worked forty years to earn my independence.
And I hadn’t saved $800,000 so someone else could decide whether I deserved respect.
They thought throwing me out would leave me powerless.
Instead, it reminded me that generosity without boundaries becomes an invitation to exploitation.
I hadn’t emptied their personal bank accounts.
I’d simply stopped allowing them to spend what wasn’t theirs.
And for the first time in years, every dollar I owned—and every peaceful morning I enjoyed—belonged to me.