My name is Margaret Wilson. I’m sixty-seven years old, a widow, and apparently the most inconvenient mother-in-law in our neighborhood.
My son, Jason, married a woman named Brittany five years ago.
Before their wedding, Brittany treated me like family. Afterward, she treated me like an unwanted tenant in her perfect suburban world.
Two years earlier, Jason called me crying.
“Mom, we found our dream house, but we’re short on the down payment.”
“How much?”
“Forty-one thousand dollars.”
That was nearly half my retirement savings.
Still, I agreed.
But my late husband had taught me something important.
“Never lend money without paperwork, even to family.”
So we signed a formal loan agreement.
Jason promised to repay me $500 monthly, with the remaining balance due after eight years. The agreement also addressed missed payments and recovery costs.
For the first year, everything seemed fine.
Then Brittany began complaining.
My garden was too colorful.
My mailbox was outdated.
My old pickup truck embarrassed the neighborhood.
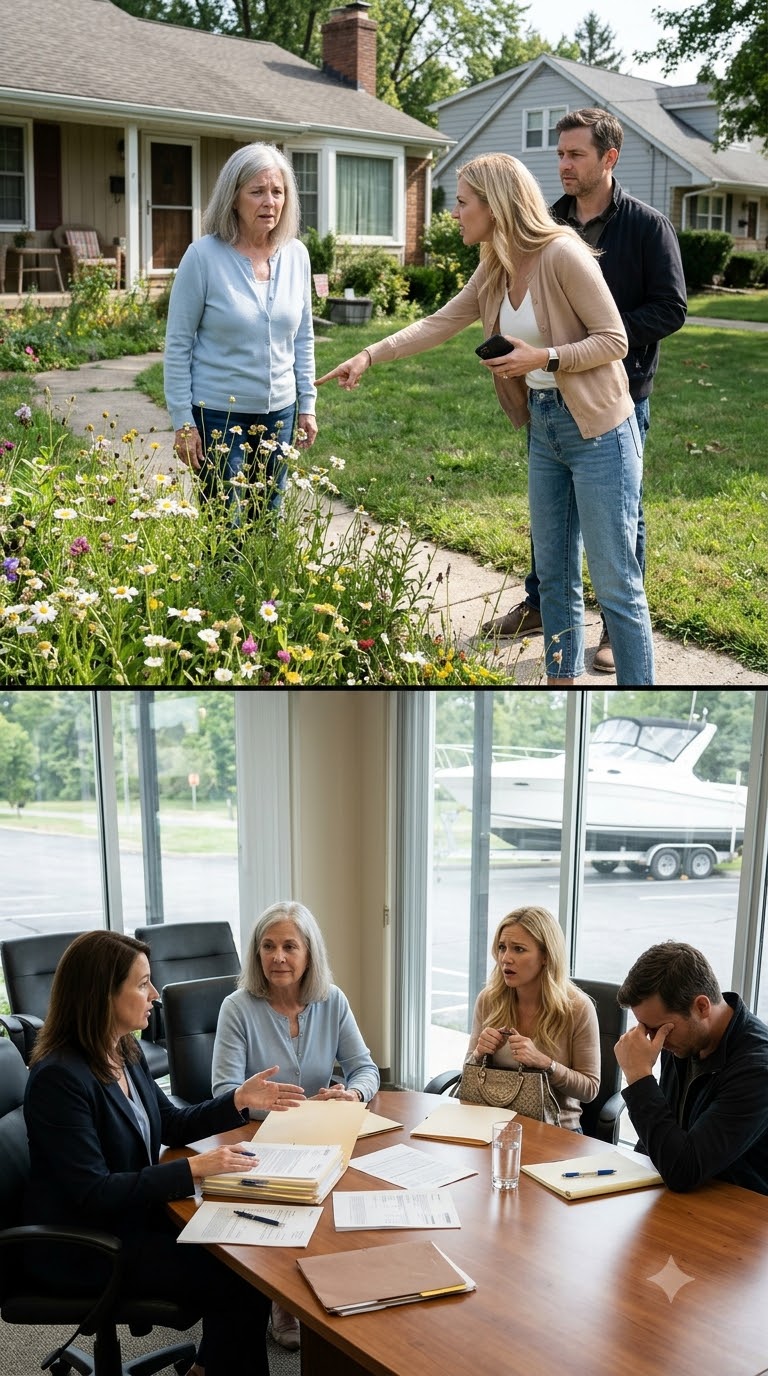
One afternoon, she appeared at my gate holding her phone.
“Margaret, your front yard looks terrible.”
I glanced at my wildflowers.
“They’re native plants, Brittany.”
“They look like weeds.”
“They attract butterflies.”
She rolled her eyes.
“Well, Jason and I are reporting your property to the homeowners’ association.”
I stared at her.
“You’d report your own mother-in-law?”
“Rules apply to everyone.”
Jason stood behind her, staring at the ground.
He said nothing.
That evening, I received an official violation notice.
The HOA demanded that I trim certain areas within fourteen days.
I felt humiliated.
Not because of the garden.
Because my son had watched his wife attack the one peaceful thing I had left.
I paid a landscaper to bring the yard into compliance.
Then I opened my financial records.
I wanted to calculate how much retirement income I’d sacrificed helping Jason.
That’s when I noticed something strange.
The last loan payment had arrived seven months earlier.
I checked again.
Seven missing payments.
Three thousand five hundred dollars overdue.
I called Jason.
“Sweetheart, have you forgotten our agreement?”
He hesitated.
“Brittany handles the finances now.”
“Then perhaps you should ask her where my money went.”
He hung up.
I sat quietly for several minutes.
Then I opened the bottom drawer of my desk and retrieved our signed loan contract.
Brittany wanted to teach me about rules.
She was about to discover that contracts had rules too.
Part 2
The next morning, Brittany called.
“Margaret, Jason says you’re demanding money from us.”
“I’m asking about seven missed payments.”
She laughed.
“Seriously? We’re family. You can’t treat us like strangers.”
“Then why did you report my garden?”
“Because your property affects our neighborhood’s image.”
I looked out at the freshly trimmed lawn.
“And unpaid debts affect my retirement.”
Her voice sharpened.
“You’re not getting another cent until you stop harassing us.”
I said nothing.
She continued.
“Besides, that money was practically a gift.”
“No, Brittany. Your husband signed a loan agreement.”
“Good luck proving it.”
She disconnected.
I contacted my longtime attorney, Robert Hayes.
He reviewed the contract, bank records, and original transfer confirmation.
“Margaret, this agreement is enforceable on its face, although recovery would depend on the terms and any defenses Jason raises.”
“What should I do?”
“We begin with a formal notice of default and an opportunity to cure.”
Within forty-eight hours, Robert sent Jason a certified letter demanding payment of the overdue installments.
The letter explained that continued default could trigger further remedies under the agreement, including possible acceleration of the remaining balance after the required notice period.
I didn’t threaten anyone.
I simply followed the contract.
Brittany responded by posting photographs of my yard in the neighborhood’s private Facebook group.
“Some homeowners think they’re above community standards.”
Several neighbors defended me.
One wrote, “Margaret’s garden is beautiful. It’s also a certified pollinator habitat.”
Another asked why Brittany was targeting an elderly widow.
Brittany deleted her post.
Then she made a bigger mistake.
She sent me a message.
“We’re not paying back that money. Jason says you gave it to us because you wanted grandchildren.”
I stared at the screen.
Grandchildren.
I’d never made such a condition.
I saved the message.
Later that evening, I received a call from my neighbor, Linda.
“Margaret, did you know Brittany and Jason bought a new boat?”
My stomach dropped.
Linda sent me a photograph.
There stood Jason beside a gleaming twenty-eight-foot motorboat.
Brittany had captioned it:
“Hard work pays off!”
The boat had been purchased three months after their payments to me stopped.
I forwarded the photograph to Robert.
He cautioned me that buying a boat didn’t automatically prove wrongdoing.
But it contradicted Brittany’s repeated claims that they couldn’t afford any payments.
Then Robert discovered something important.
The loan agreement contained a clause requiring Jason to provide updated financial information after a sustained payment default, subject to reasonable notice.
Robert requested those records.
Jason ignored him.
Instead, Brittany arrived at my house.
“You need to back off,” she hissed.
“Why?”
“Because Jason is your only son.”
I met her eyes.
“That didn’t stop him from breaking his promise.”
She stepped closer.
“If you sue us, you’ll never see your grandchildren.”
I felt the threat like a knife.
But I remained calm.
“That’s your decision, Brittany. The debt is his responsibility.”
She stormed away.
That night, Robert called.
“Margaret, the cure deadline is approaching. If they don’t respond, we’ll have grounds to proceed.”
I looked at my husband’s photograph.
“I gave my son money because I loved him,” I whispered.
“But I won’t let him use that love to bankrupt me.”
Part 3
The deadline passed without payment.
Robert filed a civil lawsuit seeking the overdue amount and enforcement of the loan agreement.
Jason and Brittany finally hired an attorney.
Their first response claimed the $41,000 had been an unconditional family gift.
Robert submitted the signed contract.
Then came the bank records.
Fourteen monthly payments identified as loan repayments.
Messages from Jason acknowledging the debt.
And Brittany’s statement that they had decided not to pay.
Their argument became considerably weaker.
During mediation, Jason refused to look at me.
Brittany sat beside him, clutching an expensive handbag.
“This is ridiculous,” she announced. “She’s destroying her son’s future over money she doesn’t even need.”
I looked at her.
“How much do you think a retired widow needs, Brittany?”
She shrugged.
“You own your house.”
“So?”
“You don’t have a mortgage.”
I leaned forward.
“That doesn’t make my retirement savings yours.”
The mediator intervened.
Robert presented the payment history and explained our requested remedies.
Jason’s attorney quietly reviewed the documents.
Then he asked to speak with his clients privately.
Twenty minutes later, Brittany returned looking furious.
Jason looked frightened.
Their attorney spoke carefully.
“My clients are prepared to discuss a structured settlement.”
Brittany snapped.
“We are not selling the boat!”
Everyone turned toward her.
Jason closed his eyes.
“Brittany, please.”
That was when I understood.
The boat mattered more to her than honoring a promise to her husband’s mother.
I placed my hands on the table.
“I’m not interested in humiliating either of you. I want my money repaid according to a realistic, enforceable agreement.”
Jason finally looked up.
“Mom, I didn’t think you’d actually sue me.”
My voice trembled.
“And I didn’t think you’d stop paying me while buying luxury toys.”
His eyes filled with tears.
Brittany interrupted.
“Don’t fall for her guilt trip!”
Jason turned toward her.
“Enough!”
The room fell silent.
“For seven months, you’ve told me Mom could afford to wait,” he said. “You said she’d never take action.”
Brittany stared at him.
“Jason!”
He shook his head.
“You convinced me to ignore the payments. But I signed that contract. Not you.”
For the first time, my son accepted responsibility.
After several hours, we reached a settlement.
Jason acknowledged the outstanding balance and agreed to resume payments under a revised schedule secured by a consent judgment that could be enforced if he defaulted again.
They also agreed to reimburse part of my documented legal expenses.
To make the initial payment, Jason sold the boat.
Brittany was furious.
But the debt was no longer something they could simply ignore.
Three months later, I received a letter from the homeowners’ association.
A review had confirmed that my registered native-plant garden complied with the community’s applicable landscaping provisions after minor adjustments.
The earlier violation was closed.
Several neighbors even asked me for gardening advice.
I began hosting monthly workshops about native plants.
Meanwhile, Jason and Brittany’s marriage deteriorated.
Without my financial support, their spending habits became impossible to maintain.
They sold their second vehicle and canceled an expensive vacation.
Eventually, Jason moved into a small apartment.
He continued making his required payments.
One afternoon, he visited me alone.
“Mom, I owe you an apology.”
I handed him a cup of coffee.
“I’m listening.”
He looked toward the garden.
“I should’ve defended you. I should’ve paid you. And I should never have let Brittany threaten you with the kids.”
I nodded slowly.
“That hurt more than the money.”
“I know.”
For a while, we sat together without speaking.
Then he asked whether he could bring the children next weekend.
I smiled.
“I’d like that.”
Six months later, my garden was more beautiful than ever.
Butterflies floated above purple coneflowers.
My grandchildren chased each other along the stone path.
And every month, a payment arrived in my bank account exactly as agreed.
Brittany still avoided me.
That was perfectly fine.
I didn’t need her approval.
I needed peace.
One evening, Linda stopped beside my garden gate.
“Margaret, remember when Brittany threatened to report your yard?”
I laughed softly.
“How could I forget?”
Linda smiled.
“Looks like you won.”
I gazed at the flowers my husband and I had planted years earlier.
“No,” I replied. “I simply stopped letting people mistake my kindness for permission.”
Because my daughter-in-law had tried to teach me a lesson about keeping things in order.
And in the end, I had done exactly that.
My garden was beautiful.
My finances were protected.
My son was finally taking responsibility.
And the woman who once threatened me over a few wildflowers had learned that some promises couldn’t be buried beneath the weeds.