PART 1: THE HUMILIATION
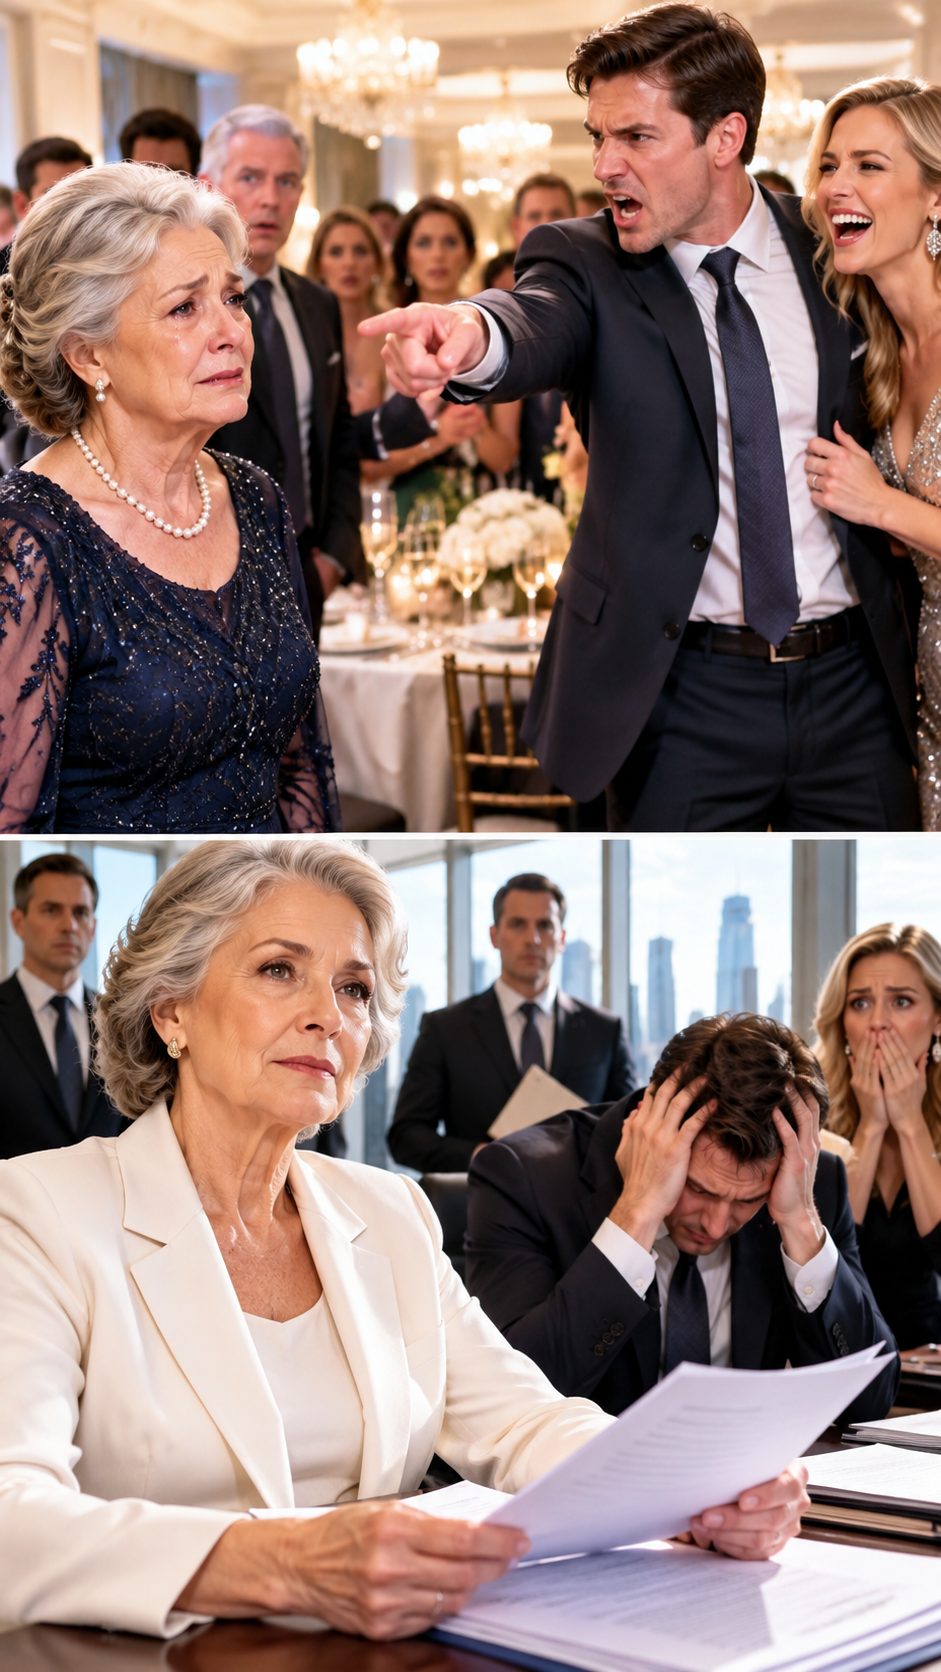
Thirty-six people watched my son point toward the service entrance and tell me I was embarrassing him. Not one of them knew I had paid for the champagne in their glasses.
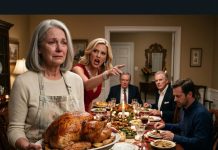
The occasion was Daniel’s fortieth birthday, held in a private ballroom overlooking Chicago. Crystal chandeliers glittered above investors, contractors, and his wife Brooke’s wealthy relatives. Daniel stood beneath a banner announcing the tenth anniversary of Hartwell Development, the construction company he liked to say he had built with his bare hands.
I wore my best navy dress and the pearl earrings my late husband had given me. Before dinner, I covered a $6,700 catering balance after Daniel claimed his company card was frozen. He promised repayment Monday, like countless times before. At sixty-five, I had learned that an elegant dress could not protect a woman from her own child.
When the photographer arranged a family picture, I stepped beside Daniel. Brooke intercepted me with a smile sharp enough to cut glass.
“Immediate family only, Nora.”
“I’m his mother.”
“Then you understand why this matters,” she whispered. “Please don’t make a scene.”
Daniel heard everything. Instead of defending me, he raised his glass.
“Everyone, my mother still thinks paying a few bills entitles her to run my life.”
Laughter scattered across the room. My cheeks burned.
“Daniel,” I said quietly, “that isn’t fair.”
He turned toward the thirty-six guests. “She used to check my homework. Now she checks my accounts. Some parents just can’t accept that their children have surpassed them.”
Brooke covered her mouth, delighted. Somebody murmured, “Poor Daniel.”
Then my son delivered the sentence I would never forget.
“You’re not one of the people who built this company, Mom. You’re just the woman who keeps asking to be thanked. Go sit by the service door before you embarrass us again.”
The room went silent. Even the pianist stopped.
I looked at the boy I had carried through emergency rooms, the young man I had comforted after failed jobs, the father whose mortgage I had quietly kept current for six years. He met my eyes without a trace of shame. Suddenly, I understood: he wanted my money, but he could no longer bear my presence.
I wanted no plaque, only a chair beside my son. Instead, he had made an audience out of my humiliation.
I set my champagne glass on the nearest table.
“You’re right about one thing,” I said. “You’re old enough to stand on your own.”
He smirked. “Finally.”
I walked out without touching the birthday cake. In the elevator, my phone vibrated with an automatic payment reminder: DANIEL HARTWELL — $13,840 DUE MONDAY.
For the first time in six years, I smiled at that number.
PART 2: THE SILENT REVENGE
By sunrise, I had opened the spreadsheet Daniel had never bothered to examine. Every month I transferred $4,800 toward his mortgage, $1,350 for his luxury SUV, $3,200 for his company’s office lease, $1,990 for insurance and utilities, and $2,500 toward a business credit line. Thirteen thousand eight hundred forty dollars, month after month, from accounts that belonged to me.
None of those debts carried my name. I had helped because he was my son, and because each request arrived dressed as an emergency. The emergencies, I finally understood, had become his lifestyle.
I instructed my bank to end the voluntary transfers. I notified each biller that future payments were Daniel’s responsibility. Then I called my attorney, Ruth Delgado.
“Are you certain?” Ruth asked.
“He told thirty-six witnesses he built everything himself.”
“And the business loan?”
“Exactly as written. No renewal.”
Three years earlier, I had lent Hartwell Development $220,000 to keep twenty-four employees on payroll. Ruth had drafted a secured promissory note, with equipment pledged as collateral. The final payment was due in sixty days. I had intended to extend it. Now I wanted the company to honor its agreement.
Daniel called on Tuesday, laughing.
“Mom, Brooke says you stormed out like a soap-opera villain. You owe us an apology.”
“I’m not coming back to fund the performance.”
“What performance?”
“Your bills. I stopped paying them.”
The laughter disappeared.
“You can’t do that.”
“I already have.”
“You’ll ruin my credit!”
“Then pay what you owe.”
He hung up. Ten minutes later, Brooke sent a message: Stop being dramatic. Daniel’s investors know you’re financially dependent on us. Nobody will believe you.
I saved the message. I kept receipts.
That Friday, Daniel posted photographs from his birthday party with the caption, SELF-MADE MEANS NEVER NEEDING A HANDOUT. Brooke shared it, adding, SOME PEOPLE CONFUSE CONTROL WITH LOVE. Friends who had eaten dinners I paid for clicked their approval beneath both posts. I printed the screenshots and studied the bank statements.
Within a week, Daniel had missed his office rent and the payment on his SUV. He called me twenty-one times. I answered once.
“Transfer the money,” he snapped. “The bank’s reviewing my expansion loan.”
“Then give the bank accurate numbers.”
“You don’t understand business.”
I almost laughed. Before retiring, I had spent twenty-eight years as a forensic accountant investigating exactly the sort of financial misrepresentation that could destroy a loan application.
Two days later, Ruth received a startling email from the bank. It asked whether I would reaffirm my signed commitment to contribute $15,000 monthly to Hartwell Development for the next twenty-four months.
There was an attachment: a letter bearing my name, my home address, and a remarkably convincing imitation of my signature.
I had never seen it before.
Beneath the signature, in bold type, were the words IRREVOCABLE FINANCIAL SUPPORT.
Ruth called immediately. “Nora, we need to report this.”
I stared at the screen. My son hadn’t merely mistaken kindness for weakness.
He had forged my promise to keep being useful.
PART 3: THE PRICE OF BETRAYAL
The bank suspended Daniel’s expansion application while its fraud team reviewed the letter. Through Ruth, I supplied signature samples, six years of payment records, and a sworn statement that I had never agreed to finance another twenty-four months. I did not contact his clients or employees. The truth was devastating enough without my spreading rumors.
Daniel, however, demanded a meeting. He chose the same hotel ballroom, believing familiar surroundings would help him regain control. This time only Brooke, his business partner, two lenders, Ruth, and I sat around the table.
He began with an injured smile.
“Mom, we can fix this privately. You sign the commitment, restore the payments, and we forget your little tantrum.”
Ruth placed the disputed letter on the table.
“Did you submit this?” she asked.
“It’s a standard family support document.”
“Did your mother sign it?”
Daniel glanced at me. “She approved the arrangement.”
“No,” I said. “I did not.”
One lender turned the document around. “Mr. Hartwell, our records show it was uploaded from your account.”
Brooke’s face lost its color.
Daniel leaned forward. “Mom, tell them we discussed it.”
“We discussed many things,” I replied. “You never asked whether you could sign my name.”
Ruth then slid across the actual loan agreement: $220,000, secured by business equipment, due in sixty days. Daniel had represented that debt to the bank as a gift, even though his own signature appeared on the note.
His business partner, Marcus, stared at him. “You told me your mother had no money in this company.”
Daniel’s voice cracked. “She’s my mother. She wouldn’t take my business away.”
“I never wanted your business,” I answered. “I wanted my son to treat me like a human being.”
The lenders ended the meeting. The bank declined his expansion loan and referred the suspected forgery to investigators. Marcus demanded an independent review of the company’s finances. Daniel’s inflated profits vanished once my subsidies were properly accounted for.
When the loan matured, Hartwell Development could not repay me. Rather than seize equipment and leave workers stranded, I accepted a court-supervised settlement allowing a competing builder to acquire the assets, retain twenty of the twenty-four employees, and repay most of my loan. Daniel lost control of the company he had called entirely his. The workers kept their wages and their dignity. Their futures were not the price of my decision.
He sold the SUV. The house followed. Brooke separated from him after the financial investigation exposed debts he had hidden from her. Prosecutors charged him over the forged letter, and his lawyer began negotiating restitution.
Six months later, I moved into a small lakefront apartment filled with sunlight. I volunteered to teach budgeting at a community center, traveled to Vermont with an old friend, and paid my own bills without dread, at last.
Daniel sent one message: I guess you finally got your revenge.
I read it beside an open window, listening to the water.
No, I thought. Revenge was what you expected. This was freedom.